
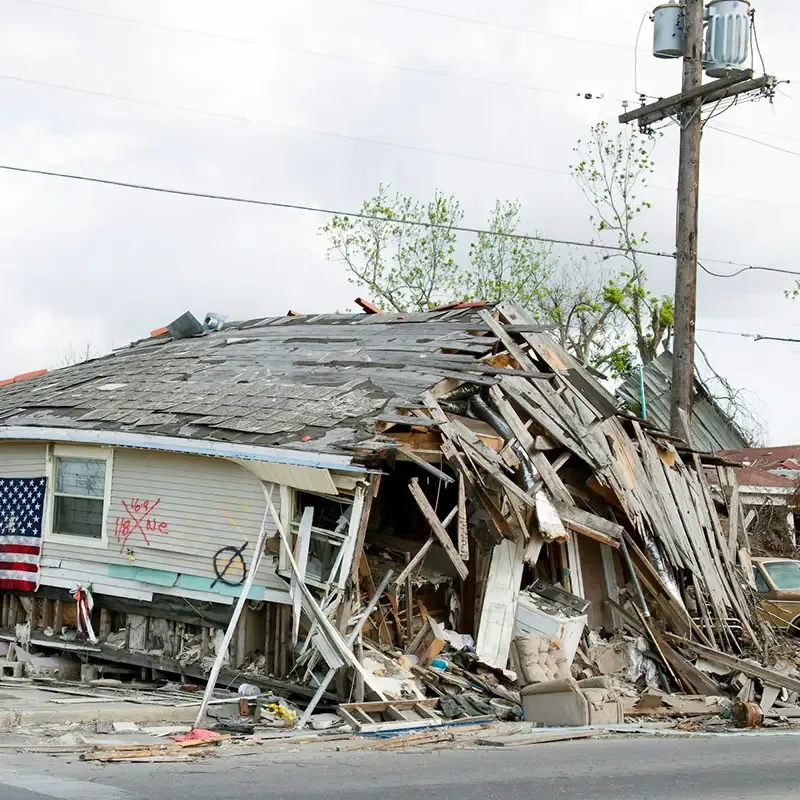
An insurance appraisal is a dispute-resolution process written into most Texas property policies. When you and your insurer agree a loss is covered but disagree on how much it costs to repair, each side names an appraiser, and a neutral umpire breaks any deadlock. An award signed by two of the three sets the amount of loss.
What is the appraisal clause in an insurance policy?
The appraisal clause is a short provision — usually a single paragraph under “Conditions” — that gives either you or your insurance company the right to demand appraisal if you “fail to agree on the amount of loss.” Texas homeowners policies (including the HO-3 and the Texas HO-B form), dwelling policies and most commercial property forms include one.
The clause typically says that each party selects a competent and disinterested (or impartial) appraiser within a set number of days, often 20, after a written demand. The two appraisers then select an umpire. If they cannot agree on an umpire, either party may ask a court to appoint one. Each side pays its own appraiser and splits the umpire’s fee.
What does an insurance appraisal decide — and what doesn’t it?
Appraisal decides the amount of loss: what it reasonably costs to repair or replace the damaged property, and in some policies the actual cash value and replacement cost figures. The Texas Supreme Court confirmed in State Farm Lloyds v. Johnson (2009) that appraisers can determine the extent of damage — for example, which shingles were damaged by hail versus wear and tear — but they do not decide coverage questions or legal liability.
| Appraisal can resolve | Appraisal does not resolve |
|---|---|
| Cost to repair or replace damaged items | Whether the policy covers the loss at all |
| Scope disputes (repair vs. full replacement) | Bad-faith or extra-contractual claims |
| Pricing, waste factors and missing line items | Policy interpretation and exclusions |
| Extent of storm-caused damage vs. pre-existing wear | Disputes over deductibles applying by law |
When should you invoke appraisal?
Appraisal is most effective when the carrier has accepted the claim but its number is far below what the repairs will actually cost. Common triggers we see across Texas include:
- A hail-damaged roof paid as a repair instead of a full replacement
- Estimates missing items such as starter strip, drip edge, flashing, ice-and-water shield, or code-required upgrades
- Unrealistically low waste factors or unit pricing for your ZIP code
- Refusal to account for matching of siding, flooring or roofing materials
- Interior water or fire damage scoped as “clean and paint” when replacement is needed
If the insurer has denied the claim outright, appraisal may still be possible in some situations — see can you invoke appraisal after a denied claim?
The insurance appraisal process, step by step
- Document the gap. Gather the carrier’s estimate, your contractor or independent estimate, photos and the policy.
- Send a written demand for appraisal that references the appraisal clause and names the dispute as the amount of loss.
- Each side names its appraiser within the policy deadline. Many Texas property owners choose TX Insurance Appraiser.
- The appraisers select an umpire, or ask a court to appoint one if they can’t agree.
- Joint inspection and estimating. Appraisers inspect, measure, and exchange line-item estimates — often built in Xactimate or Symbility.
- Negotiation. The appraisers work through differences item by item and sign an award if they agree.
- Umpire decision. If they don’t, both submit their positions to the umpire, and any two signatures create a binding award.
- Payment. The carrier pays the award, less the deductible and prior payments, subject to policy terms such as recoverable depreciation.
How long does an insurance appraisal take?
Many residential appraisals in Texas wrap up within one to three months of both appraisers being named. Complex commercial losses, disputes requiring engineers, or umpire hearings can take longer. Read our detailed guide: how long does an insurance appraisal take?
How much does appraisal cost?
You pay your own appraiser and half the umpire’s fee if an umpire is used. Fees may be hourly, flat, or a percentage of the award depending on the size and complexity of the claim. Because those costs come out of your recovery, it pays to run the numbers first — our Is Appraisal Worth It? calculator estimates your likely net gain.
Is an appraisal award binding in Texas?
Generally, yes, as to the amount of loss. Texas courts enforce appraisal awards and set them aside only in narrow circumstances such as fraud, accident or mistake, or an award made without authority. Coverage defenses may still be raised separately. Learn more in is insurance appraisal legally binding in Texas? This is general information, not legal advice.
Insurance appraiser vs. adjuster vs. public adjuster
| Role | Works for | What they do |
|---|---|---|
| Insurance company adjuster | The carrier | Investigates the claim and writes the carrier’s estimate. |
| Public adjuster | The policyholder | Manages and negotiates the entire claim for a fee. |
| Appraiser | The party that appoints them | Determines the amount of loss under the appraisal clause. |
| Umpire | Neutral | Decides disputed items when appraisers disagree. |
See the full comparison in insurance appraiser vs. adjuster.
How to prepare for a successful appraisal
- Keep every letter, estimate and email from your carrier.
- Photograph and video the damage before any repairs; a Matterport scan preserves the scene in measurable 3D.
- Save receipts for emergency repairs and mitigation.
- Track Texas prompt-payment deadlines with our claim deadline calculator.
- Work through our claim documentation checklist.
