Insurance Appraisal
We serve as your appraiser under the appraisal clause — scoping the damage, building the estimate and negotiating the award with the carrier’s appraiser.
Learn more
When your insurance company agrees the damage is covered but lowballs the amount, TX Insurance Appraiser steps in as your policyholder-side appraiser — inspecting every line item, documenting the loss in 3D, and negotiating a fair award under your policy’s appraisal clause.
Tell us about your claim. A TX Insurance Appraiser specialist will tell you honestly whether appraisal makes sense.
At TX Insurance Appraiser, we bring construction knowledge and years of claim experience to one job: proving the true amount of your loss. Insurance carriers employ trained adjusters and estimators. When you invoke appraisal, you deserve an equally qualified professional on your side of the table.
Our insurance appraisers inspect the property from the roof deck to the drywall, write a detailed line-item estimate using the same software insurers use, and meet with the carrier’s appraiser to resolve the difference. If the two appraisers can’t agree, a neutral umpire decides — and an award signed by any two of the three sets the amount of loss.
TX Insurance Appraiser combines appraisal advocacy with professional estimating and 3D documentation, so the carrier sees a complete, defensible picture of your damage.
We serve as your appraiser under the appraisal clause — scoping the damage, building the estimate and negotiating the award with the carrier’s appraiser.
Learn moreNeutral umpire services for Texas appraisals when the two appraisers reach an impasse on the amount of loss.
Learn moreImmersive, measurable 3D scans that preserve every room and every damaged surface before repairs begin.
Learn moreLine-item Xactimate estimates priced for your ZIP code — the same platform most Texas carriers use.
Learn moreSymbility estimates for carriers and claims that run on the CoreLogic platform, built to match their format.
Learn moreNot sure appraisal is right? Send us your carrier estimate and we’ll give you a straight answer at no cost.
Learn moreMost underpaid claims aren’t a single big mistake — they’re dozens of small omissions. TX Insurance Appraiser finds them.
Our lead appraiser spent his career on the policyholder side of Texas property claims, so he knows where carrier estimates typically fall short.
Waste factors, flashing, drip edge, ridge vents, code upgrades, matching, overhead and profit — we account for what is commonly left out.
Matterport, Xactimate and Symbility give the umpire and the carrier a clear, measurable record of the loss.
With hubs in Austin, Waco, Dallas and Houston, we reach homes and businesses in 288 Texas cities quickly.
Appraisal works because both sides present evidence. We build a defensible number, not an inflated one — which is what persuades umpires.
You’ll know where your appraisal stands at every step, by phone, text or email.

Joseph Dittman has spent his career on the policyholder side of Texas property claims — inspecting hail, wind, water and fire losses, writing line-item estimates, and negotiating with carrier adjusters across the state. As the lead appraiser at TX Insurance Appraiser, he brings that same field experience to the appraisal table.
His firm, Rise Public Adjusting LLC, holds Texas Department of Insurance public adjuster license #3356839, which you can verify on the TDI license lookup.
Read Joseph’s full backgroundTexas policies with an appraisal clause give both sides a faster, less expensive alternative to litigation for disputes about the amount of loss.
Send us your carrier estimate, photos and policy. We compare the scope to the actual damage and tell you whether the gap justifies appraisal.
A detailed estimate documents the true cost of repair. If the carrier still disagrees, a written demand invokes the appraisal clause in your policy.
You appoint TX Insurance Appraiser; the carrier appoints its own appraiser. Most policies set a short deadline (often 20 days) for each side to name one.
We inspect the property with the other appraiser, capture Matterport scans and measurements, and build or refine the line-item estimate.
The appraisers compare estimates line by line. Most disputes resolve here with an agreed award.
If the appraisers can’t agree, a neutral umpire reviews both positions. An award signed by any two of the three sets the amount of loss.
From Panhandle hail to Gulf Coast hurricanes, TX Insurance Appraiser handles the losses Texans actually face.
Roof, siding, gutter, window and HVAC damage that carriers often call “cosmetic” or repairable.
Lifted shingles, creased tabs, structural damage and debris impact after straight-line winds.
Wind-driven rain, roof and envelope damage, and hurricane deductible disputes on the coast.
Sudden pipe bursts, appliance leaks and hidden moisture damage behind walls and floors.
Structural fire, soot and smoke contamination, and contents disputes after residential or commercial fires.
Freeze-related pipe failures and resulting water damage like the losses after Winter Storm Uri.
With regional hubs in Austin, Waco, Dallas and Houston, TX Insurance Appraiser covers 288 cities — from Amarillo to Brownsville and El Paso to Beaumont. Looking for an insurance appraiser near you? Find your city below.
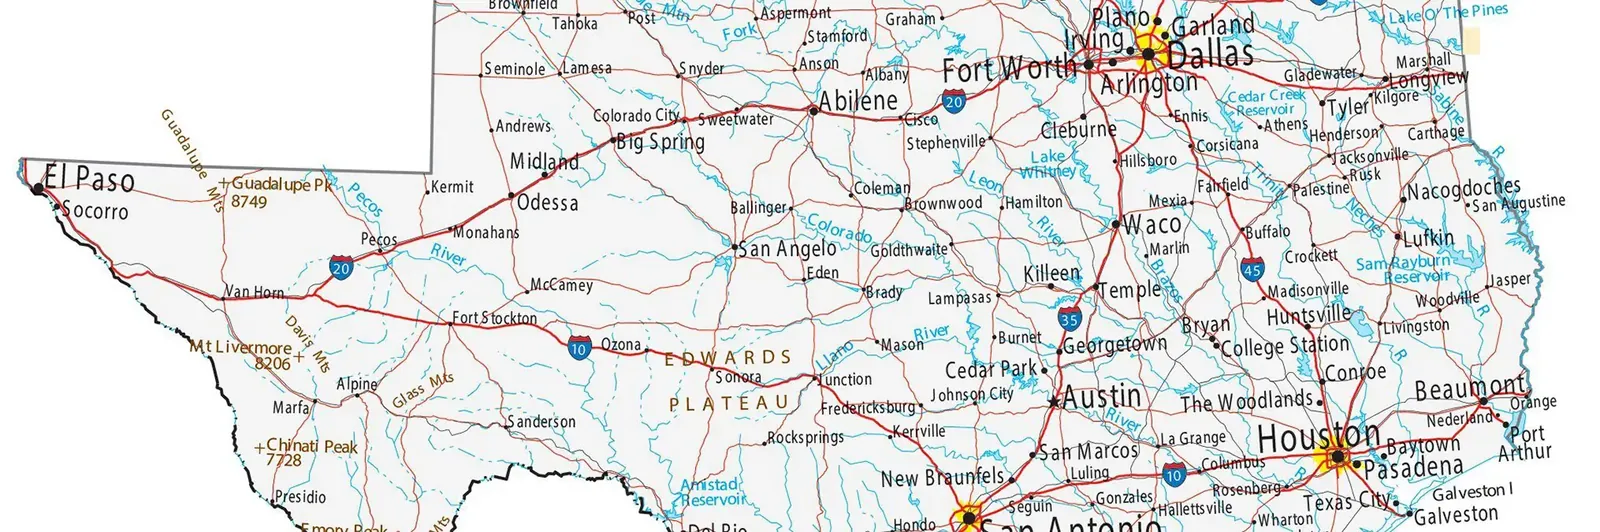 DallasWacoAustinHouston
 Harris CountyHouston Insurance Appraiser
 Dallas CountyDallas Insurance Appraiser
 Bexar CountySan Antonio Insurance Appraiser
Travis CountyAustin Insurance Appraiser
 Tarrant CountyFort Worth Insurance Appraiser
 El Paso CountyEl Paso Insurance Appraiser
 Nueces CountyCorpus Christi Insurance Appraiser
McLennan CountyWaco Insurance Appraiser
Built by TX Insurance Appraiser to help Texas property owners understand their numbers — free, private and instant.
See what your carrier should pay now (ACV) and what you can recover after repairs (RCV holdback).
Open the toolCompare the carrier’s number to your estimate and see the likely net gain after appraisal costs.
Open the toolConvert footprint and pitch into true roof squares and check the waste factor on an estimate.
Open the tool
The date of loss is the day damage actually happened. Learn what it means on an insurance claim, how it affects coverage and deductibles, and how to prove it.
Read article
How commercial fire insurance claims work in Texas: what's covered, documenting smoke, water and income losses, common disputes, and when appraisal makes sense.
Read article
Property damage pays to repair your building; business interruption replaces income lost while it is closed. Learn how the two claims differ, connect, and get underpaid after Texas storms.
Read article
How large loss insurance appraisal works in Texas for major fire, hail, hurricane and water claims, plus Texas law, evidence tips and how to choose an appraiser.
Read article
How commercial roof hail damage claims work in Texas: spotting hidden damage, navigating the claim process, avoiding disputes and knowing when appraisal helps.
Read article
Apartment and multi-family claims involve many buildings, units, and systems, so disputes are common. Learn the main conflict areas and how Texas owners use appraisal to resolve them.
Read articleTX Insurance Appraiser serves as the policyholder’s appraiser when a property owner and their insurance company agree a loss is covered but disagree on the amount. We inspect the damage, build a line-item estimate in Xactimate or Symbility, document the property, and negotiate the amount of loss with the carrier’s appraiser or an umpire under your policy’s appraisal clause.
Consider appraisal when your carrier accepts that the damage is covered but its estimate is well below what a qualified contractor says the repair will cost, and further negotiation has stalled. Common examples are hail claims paid as repairs instead of replacements, missing line items, low pricing, or disputes over matching and code upgrades.
Each side normally pays its own appraiser and splits the umpire’s fee if one is needed. Appraiser fees in Texas are commonly a percentage of the award or a flat or hourly fee depending on claim size. TX Insurance Appraiser explains its fee in writing before you sign anything, and our free Appraisal Cost Calculator helps you estimate whether appraisal is worth it.
Many Texas residential appraisals resolve in roughly 30 to 90 days after both appraisers are named, depending on how quickly inspections are scheduled, how large the gap is, and whether an umpire is needed. Large commercial losses can take longer. Having complete documentation ready usually shortens the process.
No. A public adjuster manages and negotiates the whole claim on your behalf. An appraiser is appointed under the policy’s appraisal clause to determine only the amount of loss. Our lead appraiser, Joseph Dittman, is a Texas-licensed public adjuster by background, but on an appraisal assignment he acts strictly as your appraiser.
Yes. TX Insurance Appraiser works from Austin, Waco, Dallas and Houston and serves property owners in 288 Texas cities and the rural areas between them, from the Panhandle and Permian Basin to the Rio Grande Valley, East Texas and the Gulf Coast.
Make a quick call or send your carrier estimate. We’ll review it free and tell you honestly whether appraisal can close the gap.
Tell us about your claim and Joseph will personally review it — free, with no obligation.