Key takeaways
- The date of loss is the day the damage happened — not the day you found it or reported it.
- It decides which policy period, deductible and coverage terms apply to your claim.
- Weather records, dated photos and inspections are the best proof of a date of loss.
- For hurricanes and freezes, use the day damage began and keep a written timeline.
- Date-of-loss evidence also strengthens your position in an insurance appraisal.
The date of loss is the specific day the damage to your property happened — the day the hailstorm hit, the pipe burst or the fire started. On an insurance claim, the date of loss tells the insurer which policy period, deductible and coverage terms apply, so getting it right matters as much as documenting the damage itself.
What does date of loss mean on an insurance claim?
In insurance, the date of loss meaning is simple: it is the date the covered event occurred and caused damage. If a hailstorm crossed your neighborhood on April 28, your date of loss is April 28 — even if you didn’t notice the dented gutters until June and didn’t call your carrier until July.
The date of loss is different from the day you discovered the damage and the day you reported the claim. Insurers use the date of loss to anchor almost every other decision on the file: whether your policy was active, which deductible applies, what the weather records show, and which pricing database is used to estimate repairs.
You will see the date of loss (sometimes abbreviated DOL) on your first notice of loss, your claim acknowledgment letter, the adjuster’s estimate, any proof of loss form and, if it comes to that, an appraisal award. A mismatch between those documents is one of the quickest ways for a straightforward claim to turn into a dispute.
Date of loss vs. date reported vs. date of discovery
Three dates appear on most property claims, and confusing them causes real problems. Here is how they differ:
| Date | What it means | Why it matters |
|---|---|---|
| Date of loss | The day the storm, leak, fire or other event actually caused damage | Determines policy period, deductible, weather verification and pricing |
| Date of discovery | The day you first noticed the damage | Explains any gap between the event and your report |
| Date reported | The day you gave notice of the claim to your insurer (your notice of loss) | Starts the insurer’s Texas prompt-payment clock and shows you met the “prompt notice” duty |
A claim can be perfectly valid even when the date reported is weeks or months after the date of loss — hail damage on a roof is often invisible from the ground. What matters is that you can explain the timeline and tie the damage to a real, verifiable event.
Why the date of loss matters so much
The date of loss is not a formality. In Texas property claims it drives several decisions that directly affect how much you are paid:
- Coverage period. The loss must occur while the policy is in force. A date of loss one day before your policy started — or after it lapsed — can mean no coverage at all.
- Deductible. Many Texas homeowners policies carry a separate wind and hail deductible, often a percentage of your dwelling coverage. If your deductible changed at renewal, the one in effect on the date of loss is the one that applies.
- One storm or two. Deductibles generally apply per occurrence. If two hailstorms hit a month apart, the insurer may argue they are separate losses with two deductibles — or that some damage came from an older storm before your policy began.
- Weather verification. Adjusters routinely check hail and wind reports for your address on the claimed date. If the weather data doesn’t match, expect pushback.
- Repair pricing. Estimating platforms such as Xactimate use regional price lists tied to a time period, so the date of loss influences which pricing the estimate starts from.
- Deadlines. Policy time limits — for example, the window to finish repairs and collect recoverable depreciation, or the contractual limit to file suit — are often measured from the date of loss or a related event. Check your policy language carefully.
How to determine the date of loss for a storm claim
For a burst pipe or a kitchen fire, the date of loss is usually obvious. Storm damage is harder, because Texas sees so many hail and wind events each spring that a roof can be hit more than once in a single season. When the exact date isn’t clear, build it from evidence:
- Check weather records. The National Weather Service and NOAA’s Storm Events Database list reported hail and damaging wind by county and date. Local news coverage helps too.
- Look at your own photos. Phone pictures and doorbell or security camera footage carry timestamps that can show hail falling or debris on the lawn.
- Talk to neighbors. If several homes on your street filed claims or got new roofs after the same storm, that is strong supporting evidence.
- Review contractor and inspection reports. A roofer or appraiser can often distinguish fresh hail strikes from older, weathered damage.
- Note when interior damage appeared. A ceiling stain that showed up the morning after a storm points to that storm as the date of loss.
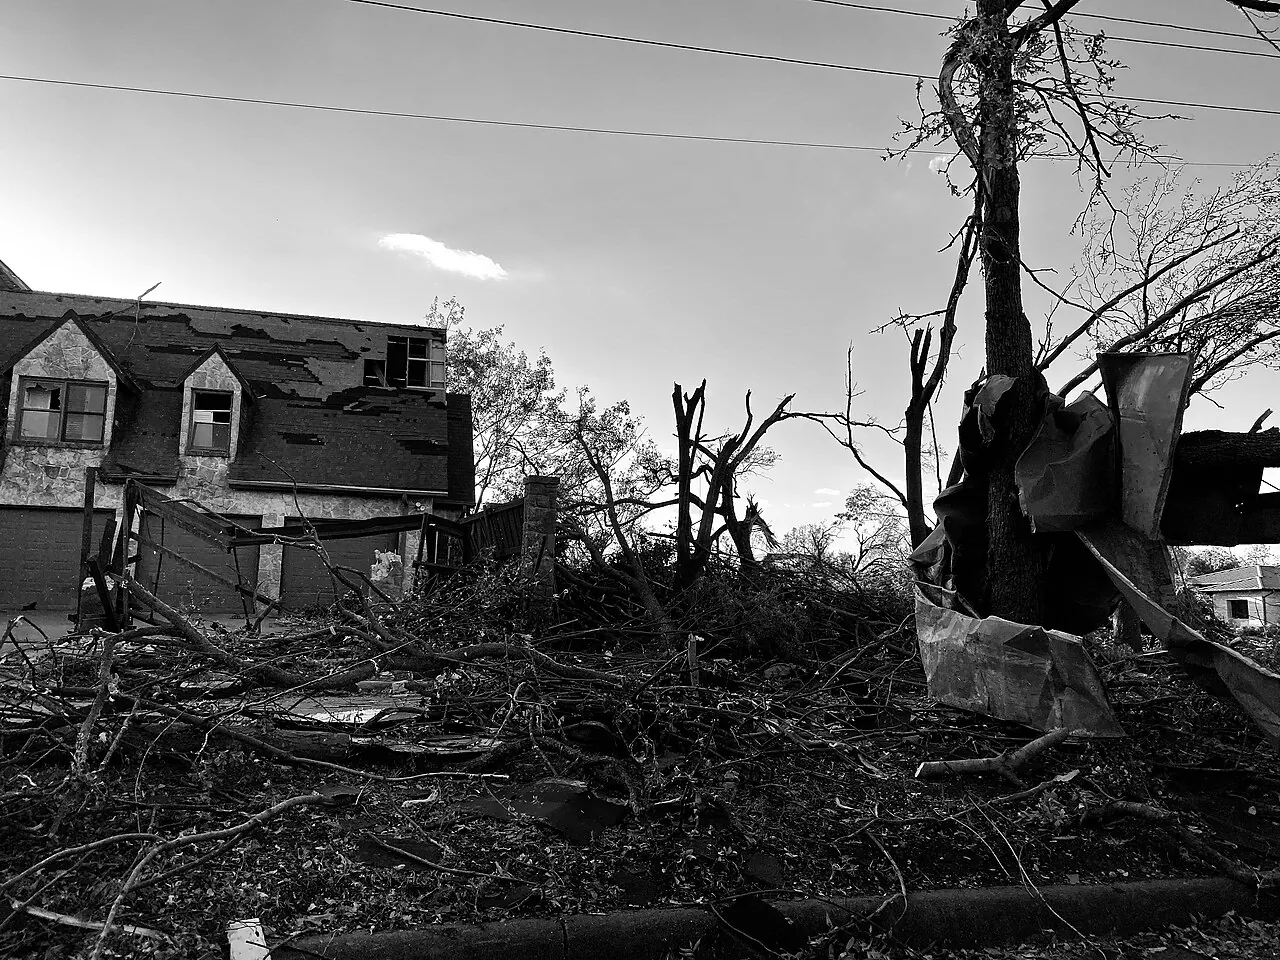
Major events make dating easy. When the October 20, 2019 tornado tore through north Dallas neighborhoods such as Preston Hollow, thousands of policyholders shared the same date of loss, and the weather service documented the storm’s path in detail. Smaller hail events require more homework — but the same evidence-first approach works.
Multi-day events: hurricanes, freezes and slow leaks
Some losses don’t happen in a single moment. Hurricanes, prolonged freezes and hidden leaks raise a practical question: which day is the date of loss?
- Hurricanes and tropical storms. Hurricane Harvey made landfall on the Texas coast on August 25, 2017, and its rain flooded the Houston area for days afterward. Claims typically use the date the damage began — often the landfall date or the first day water or wind damaged the property. Check whether your policy has a named-storm or hurricane deductible tied to the event.
- Winter freezes. During Winter Storm Uri in February 2021, many pipes froze one day and burst a day or two later. The date of loss is generally the day the pipe failed and water began causing damage.
- Slow leaks. Many policies exclude damage from repeated seepage or leakage over time. If you discover a leak behind a wall, the date of loss can become a coverage issue, so document when you found it and what you saw.
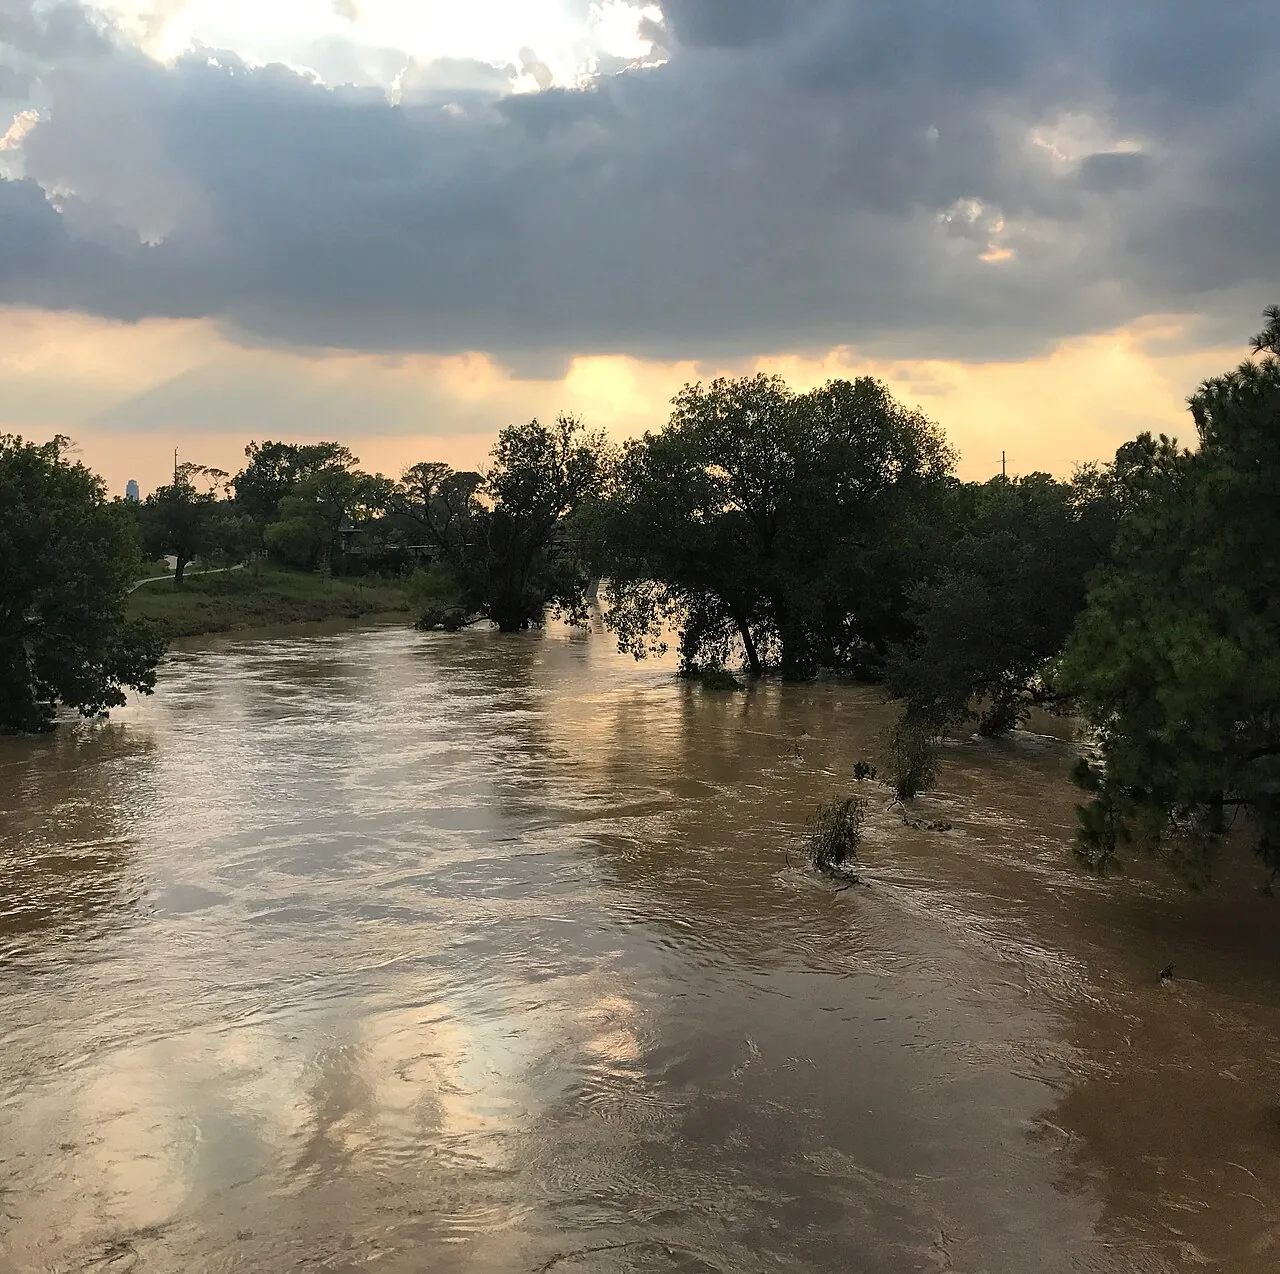
For multi-day storms, keep a simple log: when the storm arrived, when you first saw damage, what you did to prevent further damage, and when you reported the claim. That timeline answers most date-of-loss questions before they turn into disputes.
What if you don’t know the exact date of loss?
It is common — especially with roofs — not to know the precise date. In that case:
- Use the most likely date supported by weather data, and say so (“on or about April 28”).
- Don’t pick a date at random or choose one simply because it falls inside the policy period. A date that doesn’t match the weather record invites a denial.
- Ask your roofer, public adjuster or appraiser to help identify the qualifying storm.
- If you later learn the correct date, notify your insurer in writing and explain why.
An honest, well-supported estimate is far better than a guess. Insurers have tools to verify storms at your address, and a credible timeline protects your claim.
Date of loss mistakes that cost Texas homeowners money
- Reporting the discovery date as the date of loss. If no storm hit on that day, the weather won’t support the claim.
- Letting the adjuster pick a different date without checking whether it changes your deductible or coverage.
- Combining two storms into one claim — or splitting one storm into two — without understanding the deductible impact.
- Waiting too long to report. Texas policies require prompt notice, and long delays make it harder to prove which event caused the damage.
- Starting full repairs before documenting damage. Make emergency repairs to prevent further damage, but photograph everything first.
A date of loss example
Here is an illustrative example of how the date of loss plays out on a real-world style claim. A homeowner in Collin County renews her policy on March 1 with a 2% wind and hail deductible. A hailstorm crosses her neighborhood on April 28. She notices granule loss in her gutters in mid-June, calls a roofer, and reports the claim on June 20.
- Date of loss: April 28 — the day the storm hit, confirmed by local hail reports.
- Date of discovery: mid-June, when she found granules and dents.
- Date reported: June 20, which starts the insurer’s Texas prompt-payment deadlines.
- Deductible: the 2% deductible in effect on April 28 applies.
Now imagine the adjuster lists the date of loss as June 20 instead. No hail fell that day, so the weather check fails and the claim stalls. Correcting the date in writing, with the April 28 storm report attached, puts the claim back on track. That single field can be the difference between a paid claim and a denial letter.
Where the date of loss fits in the Texas claim timeline
The date of loss starts the story, but several Texas deadlines run from later dates. Knowing which clock is which keeps you from missing a step:
| Event | Typical Texas timing |
|---|---|
| Date of loss | The day the damage occurs |
| Notice of claim | As soon as practical — policies require prompt notice |
| Insurer acknowledges and requests items | Generally within 15 days of notice (Tex. Ins. Code ch. 542) |
| Insurer accepts or rejects | Generally within 15 business days of receiving requested items |
| Payment after acceptance | Generally within 5 business days |
| Weather catastrophe declared | Insurer deadlines generally extended by 15 days |
These deadlines are general rules; your policy and the facts of your claim control. For a deeper look at reporting itself, read our guide to the notice of loss and first notice of loss (FNOL).
How the date of loss affects insurance appraisal
If you and your carrier agree the damage is covered but disagree on the amount, the policy’s appraisal clause lets each side appoint an appraiser. The date of loss frames that entire process. Appraisers determine the amount of loss caused by the event on that date, and in Texas they can weigh whether specific damage came from that storm or from wear and tear, as the Texas Supreme Court recognized in State Farm Lloyds v. Johnson (2009).
That makes date-of-loss evidence valuable in appraisal: weather reports, dated photos and inspection notes help show that the damage the carrier left out of its estimate came from the same covered event. Learn more in what is an insurance appraisal? and what evidence helps during insurance appraisal.
Date of loss on auto and other insurance claims
The term means the same thing outside property insurance. On an auto claim, the date of loss is the date of the accident, theft or hail event that damaged the car. It also appears on CLUE and vehicle history reports, which is why searches like “insurance loss reported” often lead back to a specific date — see insurance loss reported meaning. The key takeaway is the same: the date of loss identifies the event, and the event determines the coverage.
Next steps if your date of loss is being questioned
If your insurer disputes the date of loss, ask for the reason in writing, gather weather records for your address, and keep every photo with its original timestamp. Use our free Texas claim deadline calculator to track Chapter 542 deadlines from the day you reported the claim, and work through the claim documentation checklist.
This article is general information about Texas property claims, not legal advice. If the dispute is about coverage itself — for example, whether the policy was in force — consider speaking with a Texas attorney.
Frequently asked questions
What is the date of loss on an insurance claim?
The date of loss is the date the event that damaged your property occurred, such as the day of a hailstorm, fire or pipe burst. Insurers use it to confirm the policy was in force, apply the correct deductible, verify weather data and choose the pricing used in the repair estimate.
Is the date of loss the same as the date I reported the claim?
No. The date of loss is when the damage happened, while the date reported is when you notified your insurer. A claim can be reported weeks after the date of loss, as long as you can explain the timeline and the damage is tied to a real event your policy covers.
What if I do not know the exact date of loss?
Use the most likely date supported by weather records and dated photos, and describe it as on or about that date. Avoid guessing or choosing a date only because it falls inside your policy period. If you later confirm a different date, tell your insurer in writing and explain why.
Can the date of loss change my deductible?
It can. Deductibles generally apply per occurrence, and many Texas policies have separate wind and hail deductibles that may change at renewal. The deductible in effect on the date of loss usually applies, and two storms on two dates may each carry their own deductible.
What is the date of loss for a hurricane or freeze claim?
It is usually the day the damage began, such as landfall or the first day wind or water damaged the property, or the day a frozen pipe actually burst. Keep a written timeline of the storm, the damage you saw and the steps you took, because multi-day events invite date questions.

About the author: Joseph Dittman
Joseph is the lead appraiser at TX Insurance Appraiser and a Texas-licensed public adjuster (Rise Public Adjusting LLC, TDI license #3356839). He has spent his career inspecting hail, wind, water and fire losses and negotiating property claims across Texas. More about Joseph.
This article is general information about property insurance claims in Texas and is not legal advice. Policy language and facts vary; review your policy or consult a Texas attorney for legal questions.