Key takeaways
- Insurance loss reported means an insurer recorded a claim or loss event in an industry database.
- It does not by itself show how severe the damage was or whether it was repaired.
- Home losses appear on CLUE reports, typically for up to seven years.
- Buyers should ask for claim details, repair records, and inspections before deciding.
- You can request your own CLUE report and dispute errors.
The insurance loss reported meaning is simple: an insurance company recorded a claim or loss event involving a specific home or vehicle in an industry database. It shows that something happened, such as hail, water, fire, or a collision, but on its own it does not tell you how severe the damage was or whether it was properly repaired.
What does insurance loss reported mean?
When you see "insurance loss reported" on a property history, a CLUE report, or a vehicle history report, it means an insurer documented a loss tied to that home or car. Insurers share this information so they can see a property's or driver's claim history when deciding whether to offer coverage and at what price.
It does not automatically mean:
- The home or vehicle is still damaged
- The claim was large or expensive
- The owner was careless or at fault
- Future coverage will be denied
The key word is reported. A loss record confirms that an event was documented. It says little about the outcome unless you look at the details behind it. For a shorter overview, see our companion article on insurance loss reported meaning explained.
Loss vs. claim vs. notice of loss: what is the difference?
Insurance language can feel confusing because similar terms mean slightly different things:
| Term | What it means |
|---|---|
| Loss | The damage or event itself, such as a hailstorm damaging a roof or a pipe bursting |
| Notice of loss | The policyholder's first report of the event to the insurer |
| Claim | The formal request for payment under the policy |
| Date of loss | The date the damage occurred, which determines which policy period applies |
| Reported loss | A loss recorded in a claims database like CLUE |
Learn more about the first step in our guide to the notice of loss insurance definition.
Where does "insurance loss reported" show up?
For homes: CLUE and loss history reports
Most home insurance claims are recorded in the Comprehensive Loss Underwriting Exchange (CLUE), a database maintained by LexisNexis. A CLUE report, sometimes called a loss history report, typically shows the date of loss, the type of loss, the amount paid, and the claim status for a property or policyholder. Claims generally stay on CLUE for up to seven years.
You may run into a home's loss history when:
- Shopping for or renewing homeowners insurance
- Buying a home and reviewing seller disclosures
- Insuring a rental or investment property
- Refinancing or reviewing a policy after a claim
How to read a CLUE report
A CLUE report can look intimidating, but each entry usually contains the same handful of fields. Work through them one at a time:
- Date of loss: when the damage occurred. Recent dates carry more weight with underwriters.
- Loss type: wind, hail, water, fire, theft, liability, and so on.
- Amount paid: what the insurer paid, if anything. A zero-dollar entry may reflect a claim that fell under the deductible or was closed without payment.
- Status: whether the claim is open or closed.
- Policyholder and property: whether the entry is tied to the address, the person, or both.
Check each entry against your own records. If a loss is listed at the wrong address, shows the wrong amount, or was never actually a claim, you can file a dispute with LexisNexis and ask your insurer to correct what it reported.
For cars: vehicle history reports
On vehicle history reports, "insurance loss reported" usually means an insurer recorded a claim involving that vehicle, often from a collision, hail, flood, theft, or vandalism. It may or may not have resulted in a salvage or total-loss title. Understanding the insurance loss reported meaning on a car report helps you ask better questions. A buyer should look for the date, the type of damage, and whether repairs were documented, and should have the vehicle inspected by an independent mechanic.
What types of losses get reported?
For homes, commonly reported losses include:
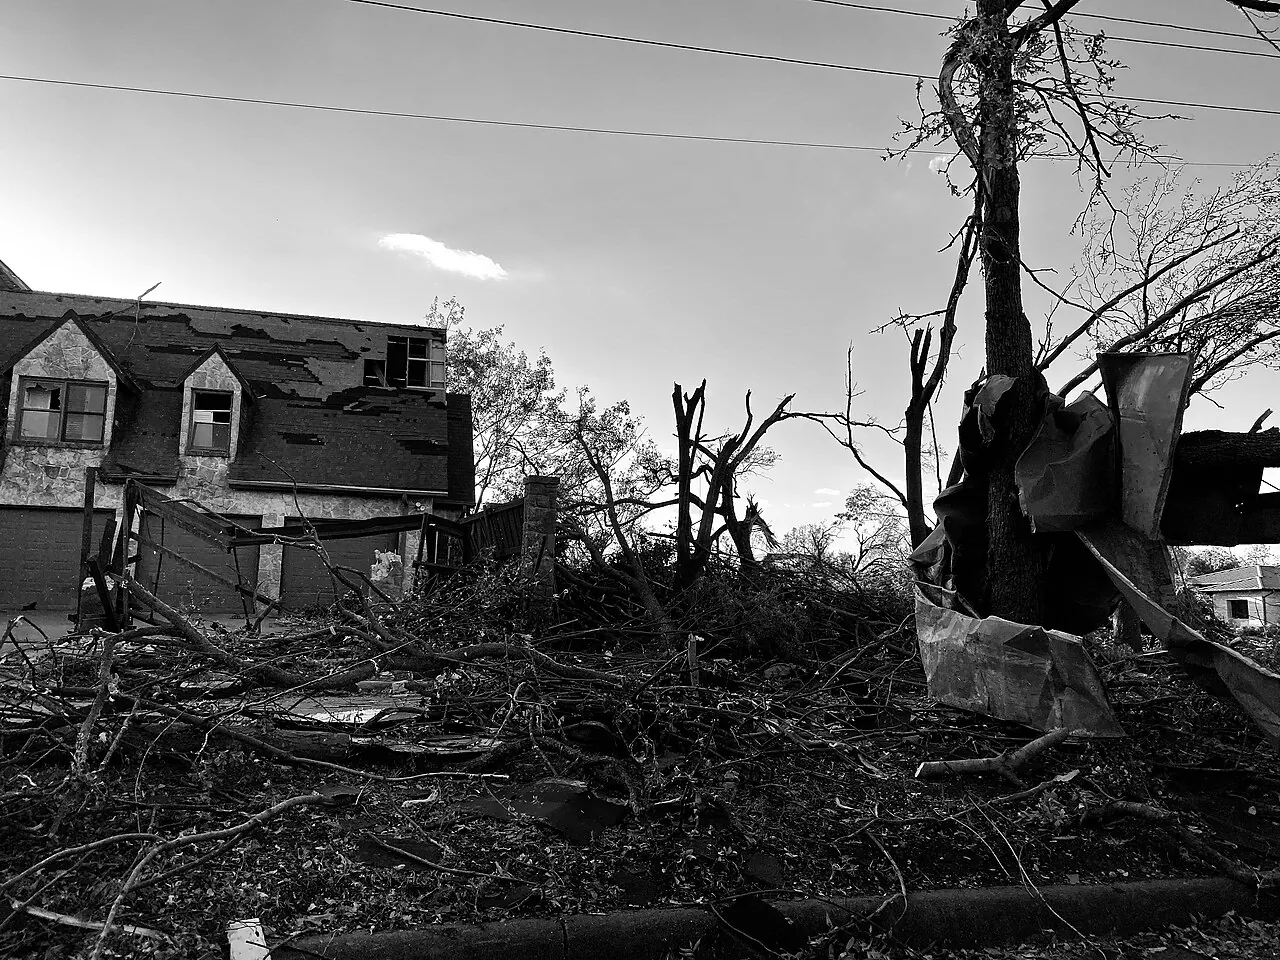
- Wind and hail damage to roofs, siding, and windows
- Water damage from leaks, burst pipes, or appliance failures
- Fire and smoke damage
- Theft and vandalism
- Mold, where covered
- Liability claims, such as an injury on the property
Each of these can trigger an "insurance loss reported" entry regardless of severity. A $900 claim for a broken window is recorded the same way as a $60,000 fire claim, which is why the details behind the entry matter so much.
Not all of these carry the same weight. A single hail claim in North Texas, where hail is common, may say little about the home's condition if the roof was replaced. Repeated water claims, on the other hand, may prompt more questions about plumbing or maintenance.
What does date of loss mean on an insurance claim?
The date of loss is the date the damage actually occurred, not the date you discovered it or filed the claim. It matters for several reasons:
- It determines which policy period, and which policy terms, apply.
- It starts the clock on certain policy deadlines, such as notice requirements and suit limitation periods.
- It helps separate damage from different storms, which affects deductibles.
- It appears on CLUE and other loss history reports.
For weather claims, storm data from sources like the NOAA Storm Events Database and dated photos help establish an accurate date of loss.
What is considered a large loss insurance claim?
There is no single legal definition. Insurers set their own internal thresholds, and a "large loss" for a homeowner may be very different from one for a commercial property. Generally, a large loss involves major structural damage, a total or near-total loss, extensive water or fire damage, or a claim that requires specialized adjusters and experts.
On a loss history report, a large claim may draw more attention from underwriters than a small one, especially if it is recent. Commercial owners dealing with major losses can learn more in our guide to large loss insurance appraisal in Texas.
How does a reported loss affect premiums and buying decisions?
For homeowners
Insurers use claim history as one factor in pricing and underwriting. A recent claim, or several claims in a short period, may lead to higher premiums or fewer coverage options. A single older claim usually has less impact.
That does not mean you should avoid filing legitimate claims. Insurance exists to pay for covered damage, and leaving hail or water damage unrepaired can lead to bigger problems and a weaker claim later. The smarter approach is to file when the damage is real and significant, document it well, and make sure the claim is paid fully so repairs are done right.
Small losses close to your deductible are a judgment call. Get a detailed estimate first. Initial estimates often miss items, and a claim that looks small at first may be larger once the full scope is documented.
For home buyers
A reported loss on a home you want to buy is a reason to ask questions, not necessarily to walk away. Ask the seller for:
- The date and type of each loss
- The insurance estimate and payment amount
- Repair invoices, permits, and contractor information
- Any warranties on new roofing or other repairs
Also ask your insurance agent to quote the home before your option period ends. The agent can run the property's loss history and tell you whether past claims will affect your premium or coverage options.
Then have a qualified home inspector, and if needed a roofer or plumber, confirm the repairs. A professionally repaired loss with good documentation can be a non-issue. A loss with no repair records deserves more scrutiny.
Insurance loss history in Texas
Texas homeowners file a large share of the country's hail and wind claims, from Amarillo and Lubbock to Dallas-Fort Worth, Austin, and San Antonio, plus hurricane claims along the Gulf Coast. Because weather claims are so common, many Texas homes have at least one reported loss in their history.
Texas has rules about how insurers may use claim history and inquiries in underwriting and pricing. The Texas Department of Insurance publishes consumer guidance on claims history and your rights. Under federal law, you can request a free copy of your CLUE report from LexisNexis and dispute information you believe is inaccurate.
If you are filing a new claim, good documentation from the start makes the record clearer for everyone. Our free claim documentation checklist walks you through what to photograph and save.
Next steps if a loss is on your record
Start by pulling your CLUE report and checking each entry for accuracy. Gather repair records for any listed losses so you can answer questions from insurers or future buyers quickly.
A reported loss is simply part of a property's history. What matters most is whether the claim was paid fairly and the damage was fully repaired. When a claim is underpaid, homeowners sometimes make partial repairs, which can cause problems later for them and for future buyers.
If you have an open claim and believe the carrier's estimate does not cover the full repair, appraisal may help resolve the amount of loss. TX Insurance Appraiser works with Texas homeowners and property owners on that question. You may also find our guide to what hazard insurance covers for a home helpful when reviewing your policy.
Frequently asked questions
What is insurance loss reported on a car history report?
It means an insurance company recorded a claim involving that vehicle, often from a collision, hail, flood, theft, or vandalism. It does not always mean the car was totaled or poorly repaired. Look for the date, the type of damage, title status, and repair records, and have an independent mechanic inspect the vehicle before buying.
How long does a reported loss stay on a CLUE report?
Home and auto claims generally remain on a CLUE report for up to seven years from the date of loss. Older claims typically carry less weight with insurers than recent ones. You can request a free copy of your own CLUE report from LexisNexis to see exactly what is listed and dispute any inaccurate entries.
Does asking my insurer a question create a reported loss?
It can in some cases, depending on how the call is recorded. Some insurers log inquiries about potential damage even if no claim is paid. Texas has rules on how insurers may use inquiries in underwriting. If you only want general information, consider asking your agent hypothetically or reviewing your policy before calling the claims line.
Should I avoid buying a house with an insurance loss reported?
Not necessarily. Many Texas homes have weather claims in their history, and a well-documented, professionally repaired loss may not be a concern. Ask the seller for claim details, repair invoices, and permits, and have a qualified inspector confirm the work. Repeated or unrepaired losses deserve closer scrutiny before you commit.
What is a loss history report?
A loss history report lists insurance claims tied to a property or policyholder over a period of years. The most common is the CLUE report from LexisNexis, which typically shows the date of loss, type of loss, amount paid, and claim status. Insurers use these reports when underwriting and pricing policies.

About the author: Joseph Dittman
Joseph is the lead appraiser at TX Insurance Appraiser and a Texas-licensed public adjuster (Rise Public Adjusting LLC, TDI license #3356839). He has spent his career inspecting hail, wind, water and fire losses and negotiating property claims across Texas. More about Joseph.
This article is general information about property insurance claims in Texas and is not legal advice. Policy language and facts vary; review your policy or consult a Texas attorney for legal questions.