Key takeaways
- Matterport turns scans into a measurable, walk-through 3D model.
- It preserves conditions before mitigation, demolition or repairs change them.
- Best paired with close-up photos, moisture data and a line-item estimate.
- It does not capture roof surfaces from above; use aerial reports for roofs.
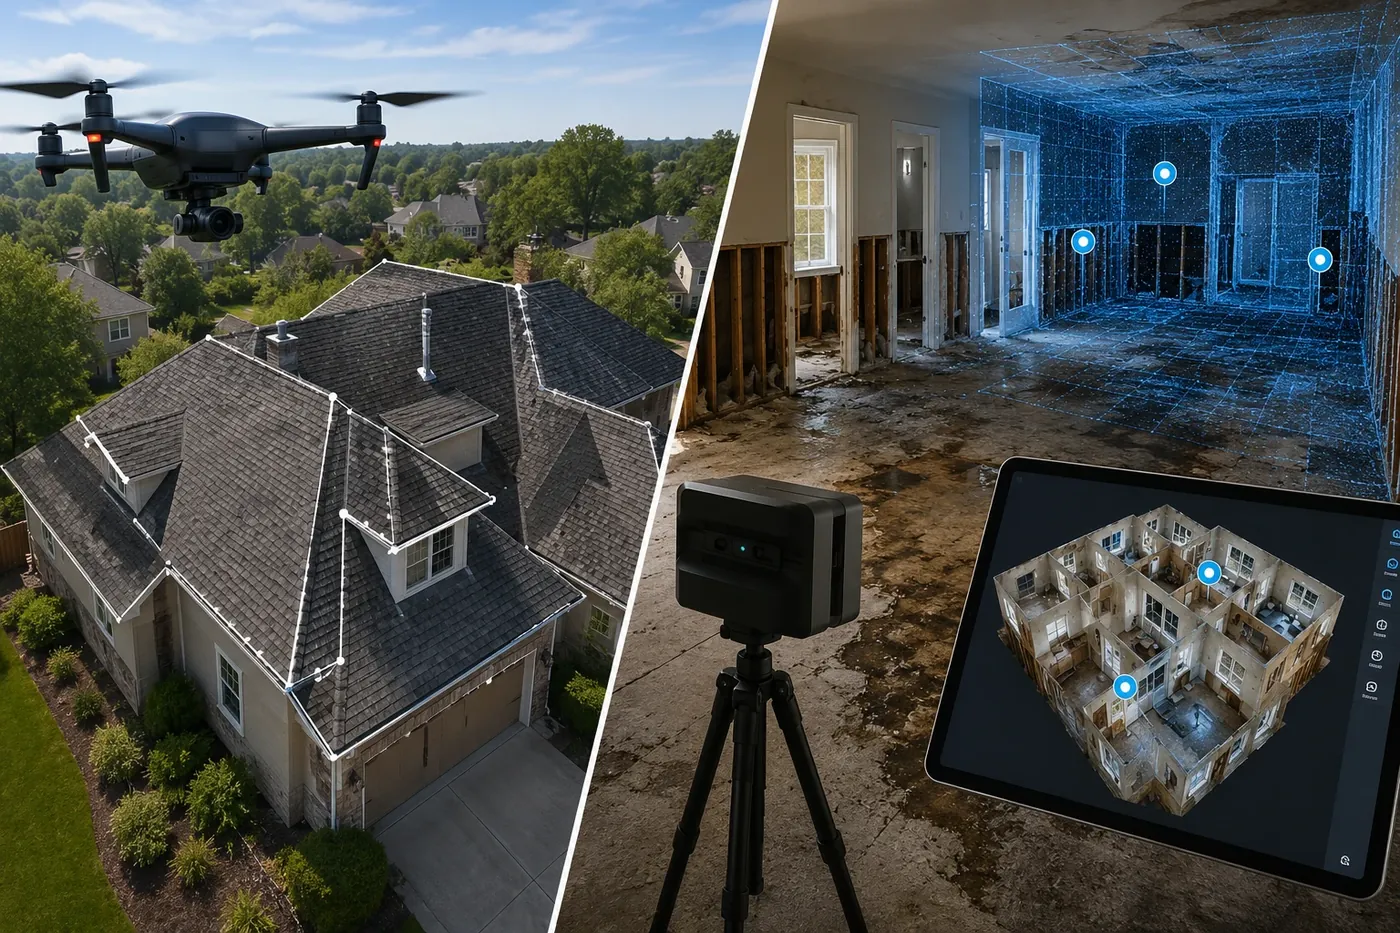
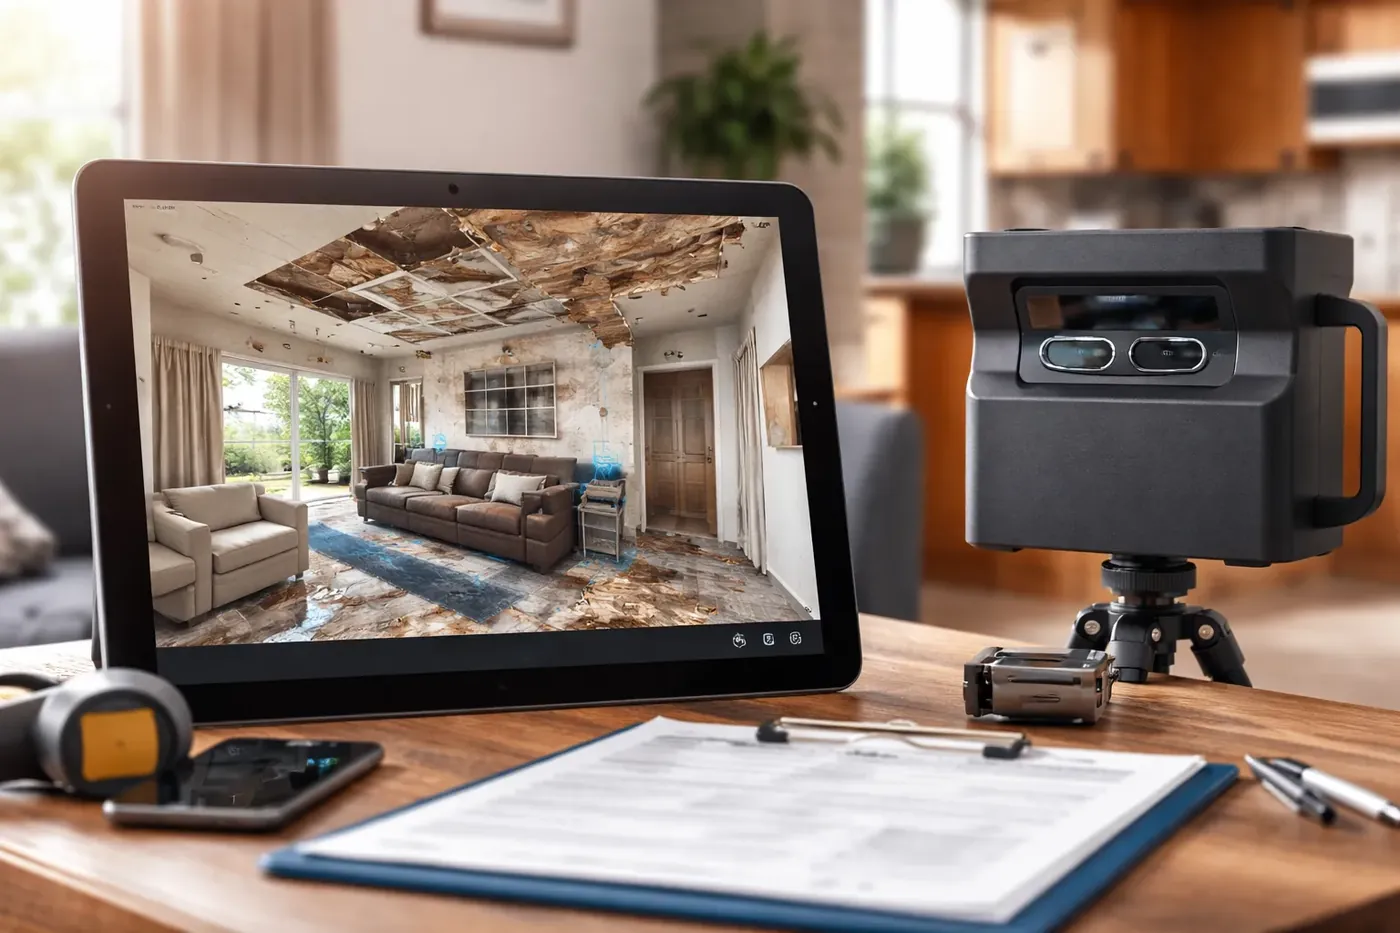
Matterport is a 3D capture platform that turns a series of scans into a measurable, walk-through digital model of a property. For insurance claims, a Matterport model preserves the exact condition of a home or building at a specific moment, with dollhouse and floor plan views and point-to-point measurements, before repairs or cleanup change anything.
Photos show pieces of a loss. A Matterport model shows the whole property and how every damaged area relates to the rest. That is why adjusters, restoration contractors and insurance appraisers increasingly use it. This guide explains what Matterport is, how it works, what a model includes, and when it is worth using on a Texas property claim.
What is Matterport, in plain terms?
Matterport is software plus compatible capture devices. An operator places a camera at a series of points throughout a property. At each point, the device captures imagery and depth data. Matterport's software then stitches those scans into a single 3D model, often called a digital twin.
Anyone with the link can then "walk" through the property online, look in every direction, switch to an overhead floor plan, view the whole structure as a dollhouse, and take measurements. The model is a record that does not fade, get lost in a phone camera roll, or depend on someone's memory of what a room looked like.
How does Matterport work?
- Plan the capture. The operator decides which rooms, exterior areas and attic spaces to include.
- Scan each position. The camera is moved through the property, typically every several feet, overlapping each scan with the last.
- Upload and process. Matterport's cloud software aligns the scans and builds the 3D model.
- Review and tag. The operator adds notes, labels and tags to specific damage.
- Share. The model is shared by link with the adjuster, contractor, appraiser or umpire.
A good capture is systematic. The operator moves in a consistent pattern, includes closets, hallways and attic access points, and captures exterior elevations where damage is visible. Skipping spaces creates gaps in the model, and gaps invite questions during a dispute. On a claim, it is better to capture an undamaged room than to leave out a room that later turns out to matter.
Capture methods used on insurance claims
- Dedicated Matterport cameras provide the most detailed depth data and are the usual choice for professional claim documentation.
- 360-degree cameras are portable and fast, with somewhat less depth detail.
- Smartphone capture works for simple, small spaces but is less suited to large or complex losses.
What does a Matterport model include?
| Feature | What it shows | Why it matters on a claim |
|---|---|---|
| Walkthrough view | Immersive navigation through every captured space | Reviewers see damage in context, room to room |
| Dollhouse view | The whole structure from outside, in 3D | Shows how damage spread across rooms and floors |
| Floor plan view | Overhead layout of each level | Supports room dimensions and estimate sketches |
| Measurement tools | Point-to-point distances | Verifies quantities for drywall, flooring, paint and trim |
| Tags and notes | Labels pinned to damage | Directs attention to specific evidence |
| Time-stamped record | Condition at the date of capture | Preserves evidence before repairs or demolition |
For a broader overview of how 3D tours are used beyond claims, read the power of Matterport.
Why do insurance appraisers care about Matterport?
Appraisal is decided on evidence. The panel, and especially the umpire, needs to understand the damage without guessing. A Matterport model helps in several ways:
- Complete context: every room is captured, not just the ones someone thought to photograph.
- Measurable evidence: quantities can be checked without a return visit.
- Preserved conditions: damage remains visible even after mitigation or repairs.
- Remote review: the other appraiser and umpire can inspect the property from anywhere, any number of times.
- Clear presentation: tagged damage makes it easier to walk the panel through disputed items.
Matterport vs. traditional claim documentation
| Photos and video | Matterport model | |
|---|---|---|
| Coverage | Only what was photographed | Every captured space |
| Context | Hard to tell where photos were taken | Spatial relationship is clear |
| Measurements | Not measurable | Point-to-point measurements |
| Close-up detail | Excellent | Good; best paired with close-up photos |
| Shareability | Large files, many folders | One link |
Matterport does not replace close-up photos. It frames them. The strongest files combine a 3D model with detailed photos, moisture readings and a line-item estimate.
How Matterport supports the claims process
Pre-loss documentation
Some owners, particularly of commercial or high-value properties, scan their buildings before any loss. A pre-loss model makes it much easier to show what existed and its condition when a later claim is filed.
Post-loss capture
The most common use is capturing the property right after a loss, before mitigation crews remove drywall, flooring or contents. Once demolition starts, the original damage is gone.
Desk reviews
Carriers and reviewers increasingly evaluate claims from the desk. A Matterport model gives a desk reviewer far more than a handful of photos.
Supplements and reinspections
When hidden damage is found during repairs, a new scan alongside the original one clearly shows what changed. That supports a supplemental insurance claim.
Using Matterport for different types of property damage
- Water damage: captures staining, swelling, and the extent of affected rooms before dry-out and demolition. Pair with moisture maps.
- Fire and smoke: shows char, soot migration and smoke damage across rooms and floors. See fire damage basics.
- Wind and hail: documents interior leaks, ceiling damage and accessible exterior elevations. For roof quantities, an aerial report is usually better; see EagleView vs Matterport.
- Structural damage: records cracks, displacement and the layout of affected framing for engineers and estimators.
Whatever the peril, the goal is the same: capture the property as early as possible, cover every affected space and the rooms around it, and keep the model available until the claim is fully resolved.
Matterport on Texas claims
Texas properties see every major peril: hail across North and Central Texas, hurricanes and tropical flooding along the Gulf Coast, wind statewide, and winter freeze events that burst pipes. After widespread storms, mitigation and repair crews move quickly, and the original conditions can disappear within days. A prompt 3D capture keeps that evidence available for the adjuster, your appraiser and, if needed, the umpire.
Large and complex properties benefit most. Multi-story homes in the Houston and Dallas areas, commercial buildings, churches and apartment complexes can be hard to describe in photos alone. A model lets a reviewer understand the full scope in minutes.
Measurement accuracy, data control and limitations
Matterport measurements are generally reliable for estimating room dimensions, wall areas and openings, and they are commonly used to support line-item estimates. They are not a substitute for surveyed measurements or engineering analysis where precision is critical.
Data security and control
The account owner controls who can view a model and whether it is public, private or shared by link. Ask your provider how long models are kept and how you can download or preserve them.
Limitations to know
- Roof surfaces are not captured from above; use aerial reports or roof inspections.
- Very dark, reflective or extremely large spaces take more time and care.
- Fine details like hairline cracks still need close-up photos.
- A model shows conditions only on the capture date.
Common myths
- "It is just a virtual tour." On a claim, it is measurable, time-stamped evidence.
- "Carriers ignore it." Adjusters and reviewers regularly use 3D models; clear evidence is hard to ignore.
- "It is only for big commercial losses." It is useful on residential water and fire claims too.
How appraisers use Matterport in appraisal disputes
When a claim moves into appraisal, the panel has to agree on scope, quantities and price. A 3D model helps at each step.
- Scope: the model shows every affected room, so items the carrier missed are easy to point out.
- Quantities: measurements in the model let both appraisers check wall area, flooring, cabinetry and trim against the estimates.
- Condition: tagged damage shows the severity that justifies replacement over repair.
- Umpire submissions: instead of describing a room, the appraiser sends a link to the exact spot in the model.
Consider an illustrative scenario. A burst supply line floods a two-story home. Mitigation crews remove wet drywall, baseboards and flooring within three days. Months later, the carrier's estimate covers drywall in two rooms, but the homeowner believes water reached the hallway, a closet and part of the kitchen. If the home was scanned before demolition, the model shows staining and swelling in each of those areas, with measurements. Without it, the dispute turns on memories and a few phone photos. That difference is often what a strong appraisal evidence file comes down to.
A model also reduces the need for repeated site visits. The other appraiser and umpire can review the same spaces as many times as they need, which helps keep the appraisal moving.
Is Matterport worth it for your insurance claim?
Matterport makes the most sense when the loss is interior-heavy, when demolition or cleanup is about to start, when the property is large or complex, or when the claim is likely to be disputed or go to appraisal. For a small, simple loss with clear photos, it may not be necessary.
TX Insurance Appraiser offers Matterport 3D documentation as part of claim and appraisal work across Texas. Joseph Dittman uses 3D models alongside line-item estimates so the other appraiser and umpire can see exactly what is being priced.
Frequently asked questions
How long does a Matterport scan of a house take?
Scan time depends on the size and complexity of the property. A typical single-family home can often be captured in a few hours, while large homes, commercial buildings or properties with many damaged areas take longer. Processing in Matterport's cloud adds additional time before the model is ready to share with adjusters or appraisers.
Do insurance adjusters accept Matterport models as evidence?
Many adjusters, restoration contractors and reviewers use Matterport models, and they are increasingly common on property claims. A model is not automatically decisive, but it gives the carrier a complete, measurable view of the damage. It is most persuasive when paired with close-up photos, moisture readings and a detailed line-item estimate.
Can Matterport be used for a pre-loss home inventory?
Yes. Scanning a home or commercial property before any loss creates a record of finishes, contents and condition. If a claim happens later, the pre-loss model helps show what existed and its condition. Keep the model link and any downloads in a safe place outside the property.
Is Matterport accurate enough for an insurance estimate?
Matterport measurements are generally reliable for room dimensions, wall areas and openings, which is what most estimates need. Estimators often use them to build or verify sketches. For roof measurements, structural engineering or situations requiring survey-level precision, other tools and methods should be used alongside the model.

About the author: Joseph Dittman
Joseph is the lead appraiser at TX Insurance Appraiser and a Texas-licensed public adjuster (Rise Public Adjusting LLC, TDI license #3356839). He has spent his career inspecting hail, wind, water and fire losses and negotiating property claims across Texas. More about Joseph.
This article is general information about property insurance claims in Texas and is not legal advice. Policy language and facts vary; review your policy or consult a Texas attorney for legal questions.