Key takeaways
- Waste is the extra material needed for cuts at hips, valleys, rakes, and penetrations.
- Simple gable roofs often need about 10%; complex hip roofs often need 15% or more.
- Compare tear-off and installation quantities to find the waste percentage in your estimate.
- Waste disputes are amount-of-loss issues that appraisal can resolve.
Roof waste factors affect insurance estimates by increasing the quantity of shingles the carrier pays for above the roof's measured area. Because every roof requires cutting at hips, valleys, and edges, a waste factor that is set too low, often 10% on a roof that needs 15% or more, quietly underpays the material and installation on your claim.
Most homeowners look at the bottom line of a roof estimate and never notice the small percentage sitting next to the shingle line item. Yet that number directly controls how many squares of roofing you are paid to install. On a large or complex Texas roof, a few points of waste can mean several squares of shingles and the labor to install them.
This guide explains what roof waste is, how carriers calculate it in Xactimate, what waste percentages are typical for different roof designs, and how to check whether your insurance estimate includes enough.
What Is a Roof Waste Factor?
A roof waste factor is the percentage added to a roof's measured surface area to account for material that must be purchased but cannot end up as installed coverage. It is not padding. It reflects the physical reality of installing rectangular shingles on a roof with angles, intersections, and penetrations.
Waste comes from several unavoidable sources:
- Cutting shingles at hips and along valleys
- Trimming courses at rakes and eaves
- Fitting around chimneys, skylights, vents, and dormers
- Offcuts that are too small to reuse elsewhere
- Courses that must start and end in specific positions to keep the pattern aligned
A simple rectangular gable roof produces relatively little waste. A cut-up hip roof with multiple valleys, dormers, and pitch changes produces much more.
How Do Insurance Companies Calculate Roof Waste?
Most carriers and independent adjusters write roof estimates in Xactimate, using measurements from a field inspection, a satellite or aerial measurement report, or a drone survey. The estimator enters the measured roof area, and the software adds a waste percentage to the shingle line item to produce the quantity paid.
Aerial measurement reports often include a suggested waste table that shows the area at several waste percentages based on the roof's geometry. The adjuster then selects a waste figure. That selection is where many disputes begin. Some estimates default to a flat percentage regardless of complexity, while others use the measured or calculated figure.
Waste applies to installation, not tear-off
A properly written estimate removes (tears off) the measured roof area and installs the measured area plus waste. You do not tear off waste, because waste never existed on the roof. If you see the same quantity on both the removal and installation lines, check whether waste was applied at all.
Separate line items still matter
Starter strip, ridge cap, hip cap, and drip edge are generally separate Xactimate line items measured in linear feet. The waste factor on field shingles should not be used as an excuse to leave those items out. Our article on common Xactimate line items missing from roof claims covers these omissions in detail.
What Are Typical Roof Waste Percentages?
There is no single correct waste factor. The right number depends on the roof's geometry and the material. The ranges below are common industry rules of thumb for asphalt shingles; your roof's actual measurements should drive the final figure.
| Roof design | Common waste range | Why |
|---|---|---|
| Simple gable (two planes, few penetrations) | About 10% | Straight rakes and eaves, minimal angled cuts |
| Hip roof | About 12% to 15% | Every hip requires angled cuts on both sides |
| Complex hip with valleys and dormers | About 15% to 20% | Many intersections, short runs, and angled cuts |
| Highly cut-up or multi-level roofs | Can exceed 20% | Frequent pitch changes and small facets |
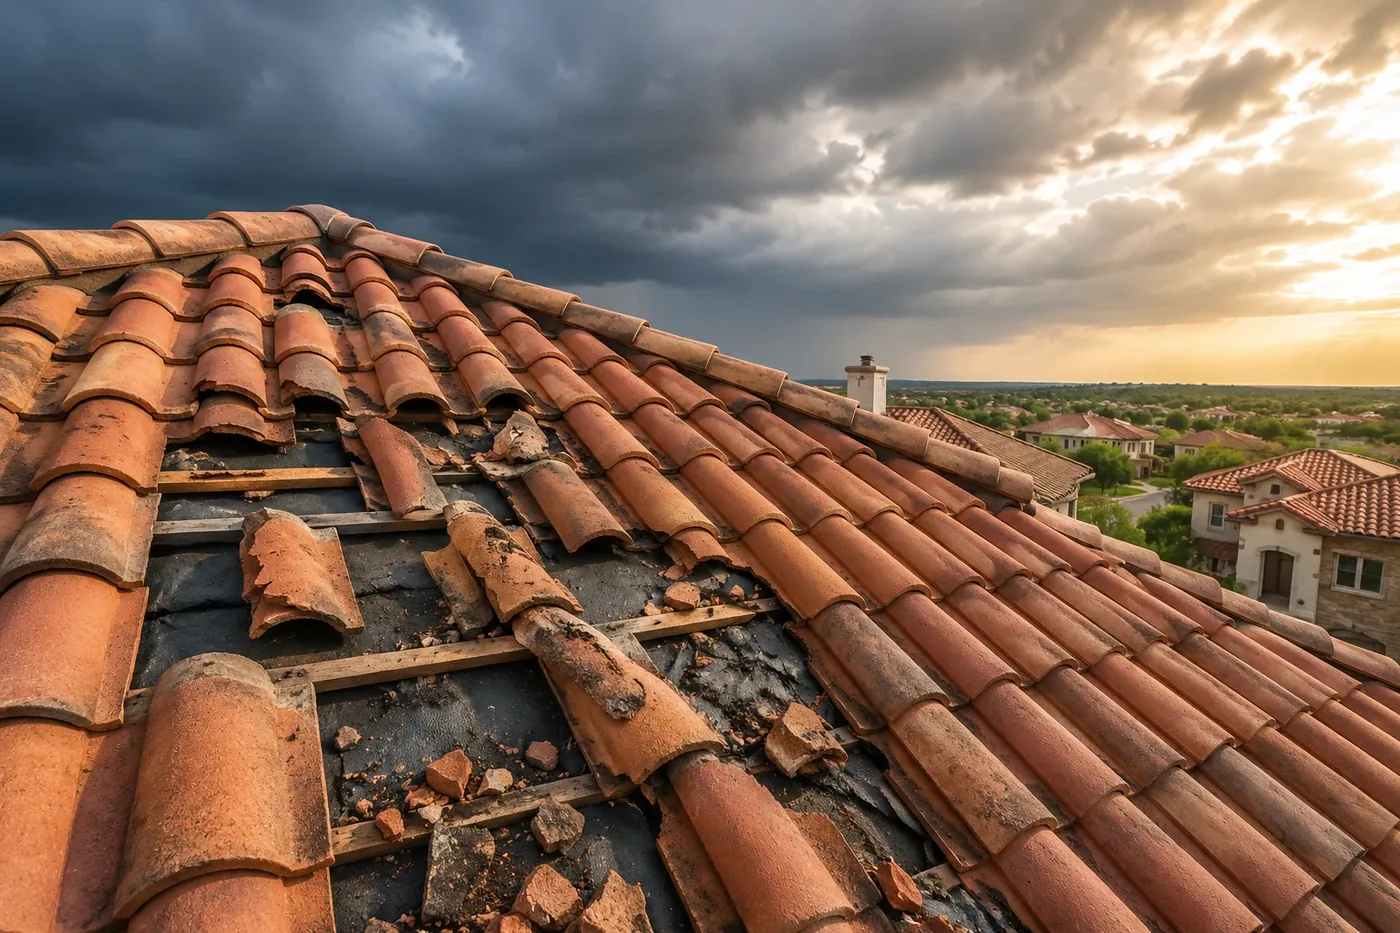
Other materials behave differently. Tile, slate, standing seam metal, and architectural shingles with specific exposure requirements can each carry their own waste considerations. See our guides on tile roof insurance appraisal in Texas for material-specific issues. Tile in particular tends to carry higher waste because of breakage during handling and the need to cut pieces at every hip and valley.
How Do Waste Factors Affect Insurance Claim Values?
Waste multiplies through the estimate. A higher shingle quantity increases the material cost, the installation labor tied to that line item, and in many estimates the overhead and profit and sales tax calculated on top of it.
Here is an illustrative example. Suppose a roof measures 30 squares (3,000 square feet):
- At 10% waste, the estimate installs 33 squares.
- At 15% waste, it installs 34.5 squares.
- At 18% waste, it installs 35.4 squares.
If the installed shingle price in that estimate were, for example, $400 per square, the difference between 10% and 18% would be roughly 2.4 squares, or close to $1,000 before tax, overhead, and profit. On a 60-square commercial or estate roof, the gap doubles. The exact dollar effect depends on your local pricing, which varies by ZIP code and by the price list month the estimator selected.
Common Waste Mistakes in Insurance Estimates
From the policyholder side, these are the waste-related problems we see most often on Texas roof claims:
- A flat default percentage applied to every roof regardless of hips, valleys, or dormers.
- Waste omitted entirely, so removal and installation quantities match.
- Waste calculated on the wrong area, such as a partial slope instead of the full replacement area.
- Inaccurate base measurements, which make even a correct waste percentage produce the wrong quantity. Our article on roof measurements for insurance claims explains how to verify them.
- Ignoring bundle rounding, since contractors buy shingles by the bundle and cannot purchase a fraction of one.
- Missing pitch adjustments, such as steep-slope charges on roofs above common thresholds, which often travel with waste disputes.
Why Contractor and Insurance Waste Calculations Differ
Contractors order material for the real job. They account for the shingle line, the manufacturer's installation rules, how the roof is cut, and the risk of running short mid-install. Carriers, by contrast, often rely on a standard percentage or software suggestion without walking every facet.
Neither side is automatically right. A contractor's material order may include extras for convenience, and an aerial report's suggested waste may underestimate a roof with unusual features. The fair answer is the waste factor supported by accurate measurements and the roof's actual geometry. Our comparison of Xactimate vs contractor estimates goes deeper into why the two documents rarely match.
Signs Your Insurance Estimate May Not Include Enough Waste
You do not need to be an estimator to spot a likely waste problem. Watch for these indicators when you review your roof estimate:
- The shingle installation quantity is identical to, or barely above, the tear-off quantity.
- The waste works out to 10% or less on a roof with several hips, valleys, or dormers.
- Your contractor's material order is several squares higher than the carrier's installed quantity.
- The estimate notes "waste included" without showing a percentage or a measurement report.
- Starter, ridge cap, or hip cap is missing, suggesting the estimator assumed the field shingle waste would cover them.
- The measured area itself looks low compared with your home's footprint and roof pitch.
Any one of these is worth a question to your adjuster. Several together usually point to an estimate that undercounts the material needed to restore your roof. Ask in writing for the measurement report and the reasoning behind the selected waste percentage, and keep a copy of every response.
Does waste change with roof pitch?
Pitch affects the true surface area of the roof, which is why a flat footprint measurement always understates roof area. Steeper roofs also make cutting and handling harder, and estimates typically include separate steep-slope labor charges above certain pitches. Pitch and waste are separate adjustments, but both need to be correct for the final square count to be right.
Roof Waste on Texas Hail and Wind Claims
Texas leads the nation in hail claims year after year, and much of the housing stock in the DFW Metroplex, Austin, San Antonio, and Houston suburbs features complex hip roofs with multiple valleys. That combination makes waste a frequent point of disagreement on Texas roof claims.
After a large storm, carriers bring in outside adjusters who may rely heavily on aerial reports and standard waste settings to keep up with volume. That is when errors creep in. If your claim involves a full replacement, ask for the measurement report the adjuster used and compare the waste figure to the roof's actual design.
Homeowners in hail-prone areas such as Dallas and Austin often find waste disputes bundled with other underscoping issues, including missing flashing, starter, and code items.
How Roof Waste Is Resolved in Insurance Appraisal
When the carrier accepts that the roof is damaged but refuses to adjust quantities, waste becomes an amount-of-loss issue, which is exactly what the appraisal clause is designed to resolve. In appraisal, each side's appraiser presents measurements, waste calculations, and supporting documentation. If they cannot agree, the umpire decides.
Strong evidence includes the aerial or drone measurement report with its waste table, field measurements, photographs of roof complexity, and the manufacturer's installation requirements. Matterport 3D scans and drone imagery can also show the number of facets and intersections clearly. Learn more about our insurance appraisal services.
How to Check the Waste Factor on Your Roof Estimate
- Find the shingle line item and note the quantity in squares.
- Find the tear-off line item and compare quantities. The difference is the waste.
- Divide the difference by the tear-off quantity to calculate the waste percentage.
- Compare that percentage to your roof's design using the table above.
- Request the measurement report and confirm the base area is accurate.
- Check related items such as starter, ridge cap, drip edge, valley metal, and steep or high charges.
Frequently asked questions
What waste factor does Xactimate use for roofs?
Xactimate does not force one waste percentage. The estimator enters the measured roof area and selects a waste figure, often based on the suggested waste table in an aerial measurement report. That is why two estimates for the same roof can show different quantities. Always compare the waste used to the roof's actual hips, valleys, and penetrations.
Is 10% waste enough for a hip roof?
Often it is not. Hip roofs require angled cuts on both sides of every hip, and many Texas homes add valleys and dormers on top of that. Common industry guidance puts hip roofs around 12% to 15% and complex hip roofs higher. The right figure should come from accurate measurements of your specific roof.
Should waste be included on roof tear-off?
No. Tear-off should equal the measured roof area, because waste material was never installed on the roof. Waste belongs on the installation line for new shingles. If both lines show the same quantity, the estimate likely omits waste, which means you are not being paid for material a contractor must buy.
How do I calculate roof squares with waste?
Divide the measured roof area in square feet by 100 to get squares, then multiply by one plus the waste percentage. For example, 2,800 square feet is 28 squares, and at 15% waste that becomes 32.2 squares. Our free roof square calculator also accounts for pitch so you can check an estimate quickly.
Can I dispute the waste factor on my insurance estimate?
Yes. Start by asking the adjuster for the measurement report and explaining why the roof's geometry supports a higher figure, with photos and a contractor's material order. If the insurer accepts the damage but refuses to adjust quantities, the disagreement is about amount of loss and can generally be resolved through your policy's appraisal clause.

About the author: Joseph Dittman
Joseph is the lead appraiser at TX Insurance Appraiser and a Texas-licensed public adjuster (Rise Public Adjusting LLC, TDI license #3356839). He has spent his career inspecting hail, wind, water and fire losses and negotiating property claims across Texas. More about Joseph.
This article is general information about property insurance claims in Texas and is not legal advice. Policy language and facts vary; review your policy or consult a Texas attorney for legal questions.