
Humble Insurance Appraiser
TX Insurance Appraiser is the Humble Insurance Appraiser property owners across Harris County call when an insurance company accepts a claim but underpays it. We inspect, estimate and negotiate a fair, binding award under your policy’s appraisal clause.
Humble Insurance Appraiser at a glance
- CountyHarris County
- RegionHouston & Upper Gulf Coast
- Nearest hubHouston
- Free reviewWithin 1 business day
- ZIP codes served77338, 77396 & surrounding
Your Humble Insurance Appraiser for Disputed Property Claims
Humble began as an oil boomtown in the early 1900s and today combines a historic downtown with established neighborhoods, the Atascocita area and fast-growing subdivisions near Lake Houston. Proximity to the San Jacinto River and George Bush Intercontinental Airport shapes the area. A Humble insurance appraiser commonly handles hurricane wind damage, tree impact and water intrusion disputes.
Hiring a Humble Insurance Appraiser gives you a professional who speaks the carrier’s language — line-item estimates, pricing databases and policy terms — and who works for you, not the insurer.
Whether it’s a hail-battered roof, a burst pipe, a wind-damaged storefront or a fire loss, TX Insurance Appraiser documents every line item, prices it for the Humble market, and presents it to the carrier’s appraiser — or to a neutral umpire if needed.
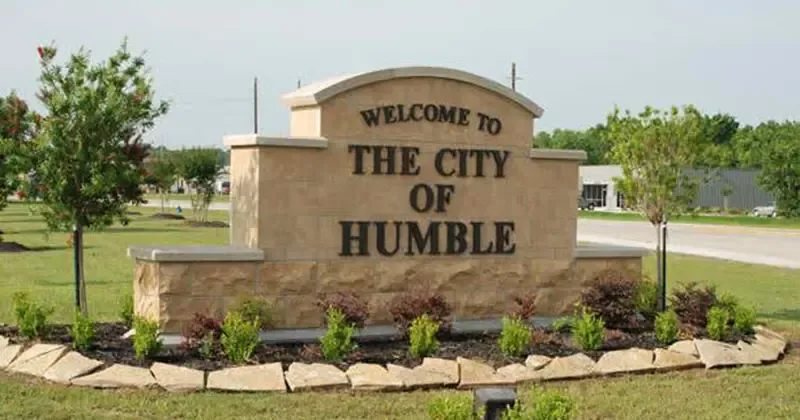
When Should You Hire a Humble Insurance Appraiser?
Appraisal is built for one specific problem — a disagreement about the amount of a covered loss. Consider calling a Humble Insurance Appraiser when:
- Your carrier accepted the claim but its estimate is thousands below your contractor’s bid.
- A storm-damaged roof was approved for spot repairs instead of full replacement.
- The estimate leaves out flashing, drip edge, code items, waste or overhead and profit.
- Interior water or fire damage was scoped as “clean and paint.”
- Negotiations with the adjuster have stalled and you want a binding decision without a lawsuit.
Appraisal doesn’t decide coverage questions or legal claims. If your claim was denied outright, read can you invoke appraisal after a denied claim?
Run the numbers first
Our free calculators show whether appraisal is likely worth it for your Humble claim — before you spend a dollar.
- Is Appraisal Worth It? Calculator
- Recoverable Depreciation Calculator
- Texas Claim Deadline Calculator
Humble Storm Risks Every Property Owner Should Know
Humble faces Gulf hurricanes and tropical storms; Hurricane Harvey in 2017 caused major flooding along the San Jacinto River and Lake Houston, and Hurricane Ike in 2008 and Hurricane Beryl in 2024 brought damaging winds and downed trees. Spring storms bring hail and straight-line winds, and Winter Storm Uri in 2021 caused frozen pipes.
Hurricanes & tropical storms
Severe storms combine wind, rain and debris, damaging the roof, envelope and interior at the same time.
Flooding & wind-driven rain
Sudden water damage hides behind walls and under floors, and scope disputes over drying and replacement are common.
Derecho & straight-line wind
Wind lifts and creases shingles, peels flashing and topples trees; tornadoes can cause structural damage that needs full replacement.
Spring hail
Hail bruises shingles, fractures tile, dents metal and cracks skylights and HVAC fins — damage carriers often underscope.
Freeze & burst pipes
Freezes burst pipes and cause sudden water losses throughout the home, often discovered days later.
Fire & smoke
Fire and smoke require detailed scopes for structural repair, cleaning, deodorization and contents.
In Houston & Upper Gulf Coast, the disputes our Humble Insurance Appraiser team sees most often involve named-storm and windstorm deductibles, wind-versus-water causation questions, and roofs and interiors damaged by wind-driven rain. Atlantic hurricane season runs June 1 through November 30, and spring squall lines bring hail and damaging straight-line winds.
Services From Your Humble Insurance Appraiser
Every service is available to Humble residential and commercial property owners.
Insurance Appraisal
Your Humble Insurance Appraiser under the policy’s appraisal clause — inspection, estimate, negotiation and award.
Umpire Services
Neutral umpire services for Humble appraisals that reach an impasse between the two appraisers.
Matterport 3D Scans
Measurable 3D documentation that preserves interior damage before repairs begin.
Xactimate Estimates
Line-item estimates priced for Humble-area ZIP codes in the format carriers use.
Symbility Estimates
Estimates that match carriers using the Symbility platform for direct comparison.
Free Claim Review
Send your carrier estimate — we’ll tell you honestly whether appraisal can close the gap.
How the Appraisal Process Works in Humble
Free claim review
Share your carrier estimate, photos and policy. Your Humble Insurance Appraiser compares the scope to the real damage and tells you whether appraisal is worth it.
Written demand for appraisal
A written demand invokes the appraisal clause. Most policies give each side a short window — often 20 days — to name an appraiser.
Inspection & documentation
We inspect your Humble property with the carrier’s appraiser, capture measurements and Matterport scans, and build a line-item estimate.
Negotiation
The two appraisers compare estimates line by line. Most disputes resolve here with a signed award.
Umpire if needed
If the appraisers can’t agree, a neutral umpire — chosen by the appraisers or appointed by a court in Harris County — decides the disputed items.
Award & payment
An award signed by two of the three sets the amount of loss. Under Texas law, carriers generally must pay within five business days after agreeing to pay.
Residential & Commercial Claims in Humble
Brick and fiber-cement homes with composition or architectural shingle roofs, older frame homes near downtown and lakeside houses near Lake Houston. Commercial and retail buildings along US 59 use flat TPO or modified-bitumen roofs.
Our Humble Insurance Appraiser services cover single-family homes, townhomes, apartment complexes, HOAs, churches, retail centers and commercial buildings. Each estimate reflects the actual materials on your property — not a generic template.

Meet Your Humble Insurance Appraiser: Joseph Dittman
Joseph is a Texas-licensed public adjuster who has spent his career on the policyholder side of hail, wind, water and fire claims. His firm, Rise Public Adjusting LLC, holds TDI license #3356839. On your appraisal, he serves as your appraiser. Read his background.
Areas Our Humble Insurance Appraiser Team Serves
We work out of our Houston hub, so Humble is right in our backyard. We serve every part of Humble and the surrounding Harris County communities.
- Atascocita
- Kingwood
- Old Town Humble
- Lake Houston area
- Spring
- US 59 / I-69
- George Bush Intercontinental Airport
- Lake Houston
- San Jacinto River
Nearby cities we also serve:
Talk to a Humble Insurance Appraiser Today
Tell us about your claim. We’ll review the carrier’s estimate at no cost and give you a straight answer about whether appraisal can close the gap.
Humble Insurance Appraiser FAQs
How do I hire a Humble Insurance Appraiser?
Call TX Insurance Appraiser at +1 (254) 421-5412 or send your carrier’s estimate through our contact form. We review your claim free, explain our fee in writing, and if appraisal makes sense, you appoint us as your appraiser in your written demand or response to the carrier.
How much does a Humble Insurance Appraiser cost?
Each side pays its own appraiser and shares the umpire’s fee if one is needed. Our fee depends on the size and complexity of the Humble claim and is set out in writing before you sign. Use our free Appraisal Cost Calculator to estimate your net recovery first.
A tree damaged my Humble roof during a hurricane. Can appraisal include hidden damage like rafters?
Yes. In Humble, tree-impact claims often involve cracked rafters, damaged decking and interior water intrusion that aren't obvious at first. Appraisers on both sides should inspect the attic and interior, document hidden damage and price complete repairs. If they disagree on the amount of loss, an umpire decides. Policy limits on tree removal still apply.
How long does an appraisal take in Humble?
Many residential appraisals in the Humble area resolve within roughly one to three months after both appraisers are named. Timing depends on inspection scheduling, the size of the gap, and whether an umpire is required. Large commercial claims can take longer.
Does TX Insurance Appraiser serve all of Harris County?
Yes. Along with Humble, we serve communities throughout Harris County and the surrounding area, including Atascocita, Spring, Aldine. We work out of our Houston hub, so Humble is right in our backyard.
Helpful guides for Humble property owners
Roof Measurements for Insurance Claims: How Squares, Pitch, and Waste Affect Your Payout
Every line in a roof estimate starts with a measurement. Learn how squares, pitch, waste, and linear feet are calculated for insurance claims and how to spot errors that shrink your payout.
Read guide Roof ClaimsWhat Is Cosmetic Damage in Roofing Claims?
What cosmetic roof damage means, how it differs from functional damage, how Texas cosmetic exclusions work, and what evidence helps challenge a denial.
Read guide Roof ClaimsWhat Is Functional Damage in Roof Claims?
Functional roof damage reduces a roof’s ability to shed water or shortens its life. Learn how it differs from cosmetic damage and how to document it in Texas claims.
Read guideUnderpaid claim in Humble?
Your Humble Insurance Appraiser is one call away. Free, no-pressure review from TX Insurance Appraiser.