Key takeaways
- Functional damage impairs water-shedding ability or shortens roof service life.
- Cosmetic damage affects appearance only and is often excluded or disputed.
- Hidden mat fractures and repairability drive many functional damage disputes.
- Test square thresholds are carrier practices, not policy language.
- Appraisal can resolve how much of a roof is functionally damaged.
Functional damage in roof claims is damage that reduces a roof's ability to keep water out or shortens its expected service life. Fractured shingle mats, punctures, torn or creased shingles, and split or broken roofing materials usually qualify. Cosmetic damage, by contrast, affects appearance only. The difference often decides whether a claim is paid.
What is functional damage in roof claims?
Insurers, engineers and adjusters use "functional damage" to describe harm that impairs how a roof performs. A roof has two basic jobs: shed water and last for its expected lifespan. Damage that interferes with either one is generally considered functional.
The term matters because many claim decisions, and some policy exclusions, depend on it. If an adjuster concludes that hail marks on your roof are cosmetic, the claim may be denied or reduced even though the roof was clearly hit. If the damage is functional, the repair or replacement cost is typically covered, subject to your deductible and policy terms.
In practice, functional damage in roof claims usually comes down to two questions an adjuster or appraiser asks about each impact or defect: will this let water in now or sooner than it otherwise would, and will this roof wear out earlier because of it? A yes to either question points toward functional damage.
"Functional damage" is not always defined in the policy itself. It is an industry concept, and that is exactly why it causes so many disagreements between homeowners, contractors and carriers.
Functional vs cosmetic roof damage
The clearest way to understand functional damage is to compare it with cosmetic damage.
| Factor | Functional damage | Cosmetic damage |
|---|---|---|
| Water-shedding ability | Reduced or compromised | Not affected |
| Expected service life | Shortened | Not affected |
| Typical shingle example | Fractured mat, puncture, torn or creased tab | Surface scuffs with no mat fracture |
| Typical metal example | Puncture, fractured seam, breached coating, loose fasteners | Shallow dents with intact coating |
| Usual claim result | Covered, subject to policy terms | Often excluded or disputed |
Our companion article on cosmetic damage in roofing claims covers the other side of this line, including how cosmetic damage exclusions work.
Examples of functional roof damage by roof type
Asphalt shingles
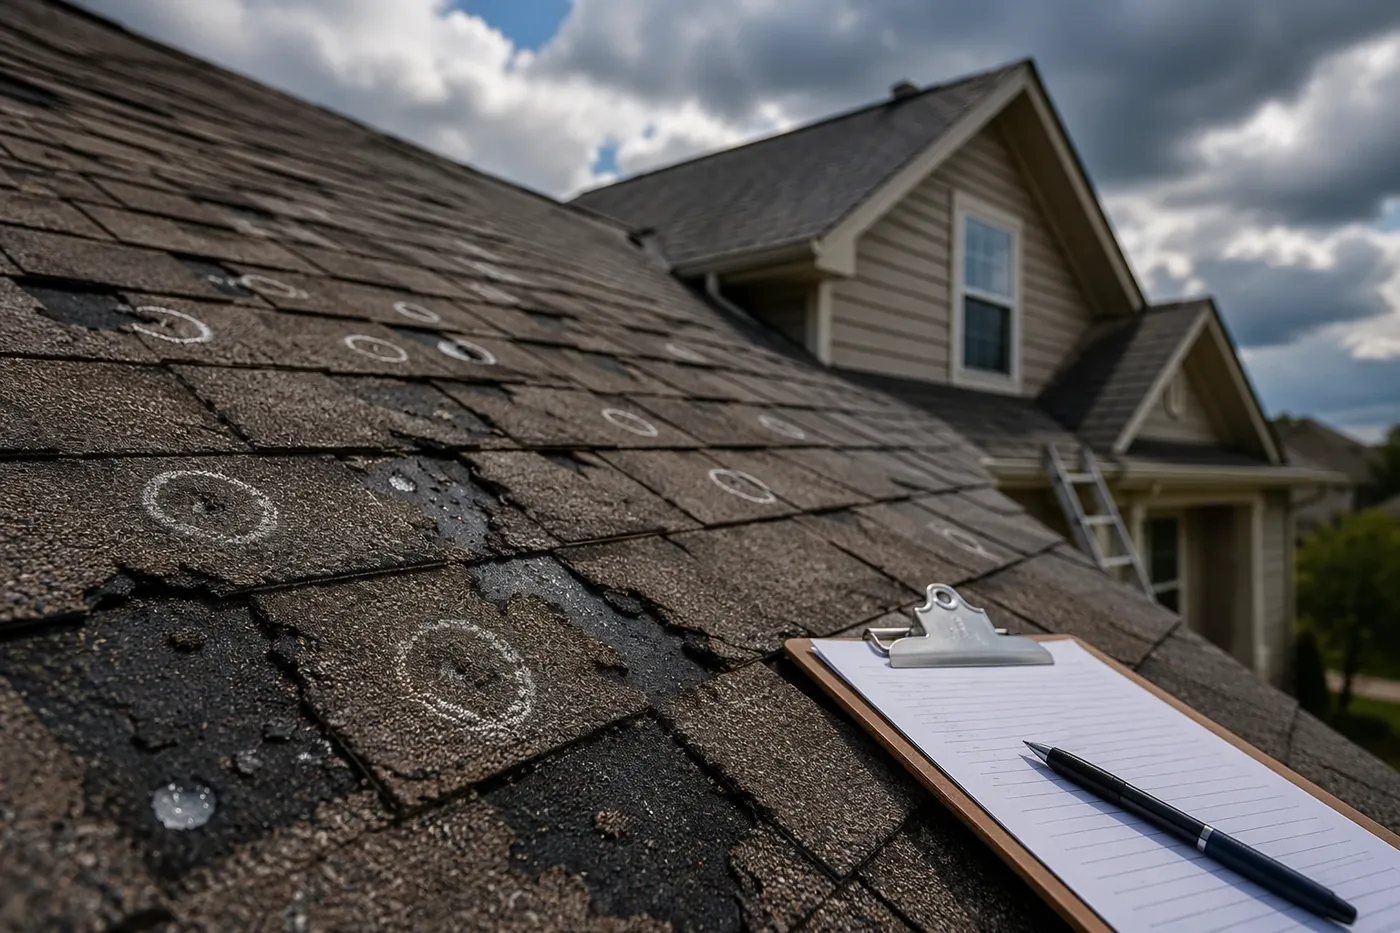
- Fractured fiberglass mat. Hail can crack the mat beneath the granules even when the surface mark looks small. A fracture creates a path for water and accelerates deterioration.
- Granule loss that exposes the mat. Granules protect the asphalt from UV. Impact areas that expose the mat age much faster.
- Punctures. Large hail or debris can punch completely through a shingle.
- Creased, torn or missing tabs. Wind can lift shingles and crease them at the nail line, weakening them even after they lie flat again.
- Broken seal strips. Shingles that no longer bond can lift and blow off in the next storm. Carriers sometimes dispute this item, so documentation matters.
Metal roofs
- Punctures or tears in panels
- Fractured or deformed seams and laps that allow water entry
- Dents that crack or breach the coating and expose metal to corrosion
- Loosened or damaged fasteners and washers
Metal roofs are where the cosmetic-versus-functional debate is sharpest. Read more in our guide to the insurance estimate for metal roof damage.
Tile, slate and wood
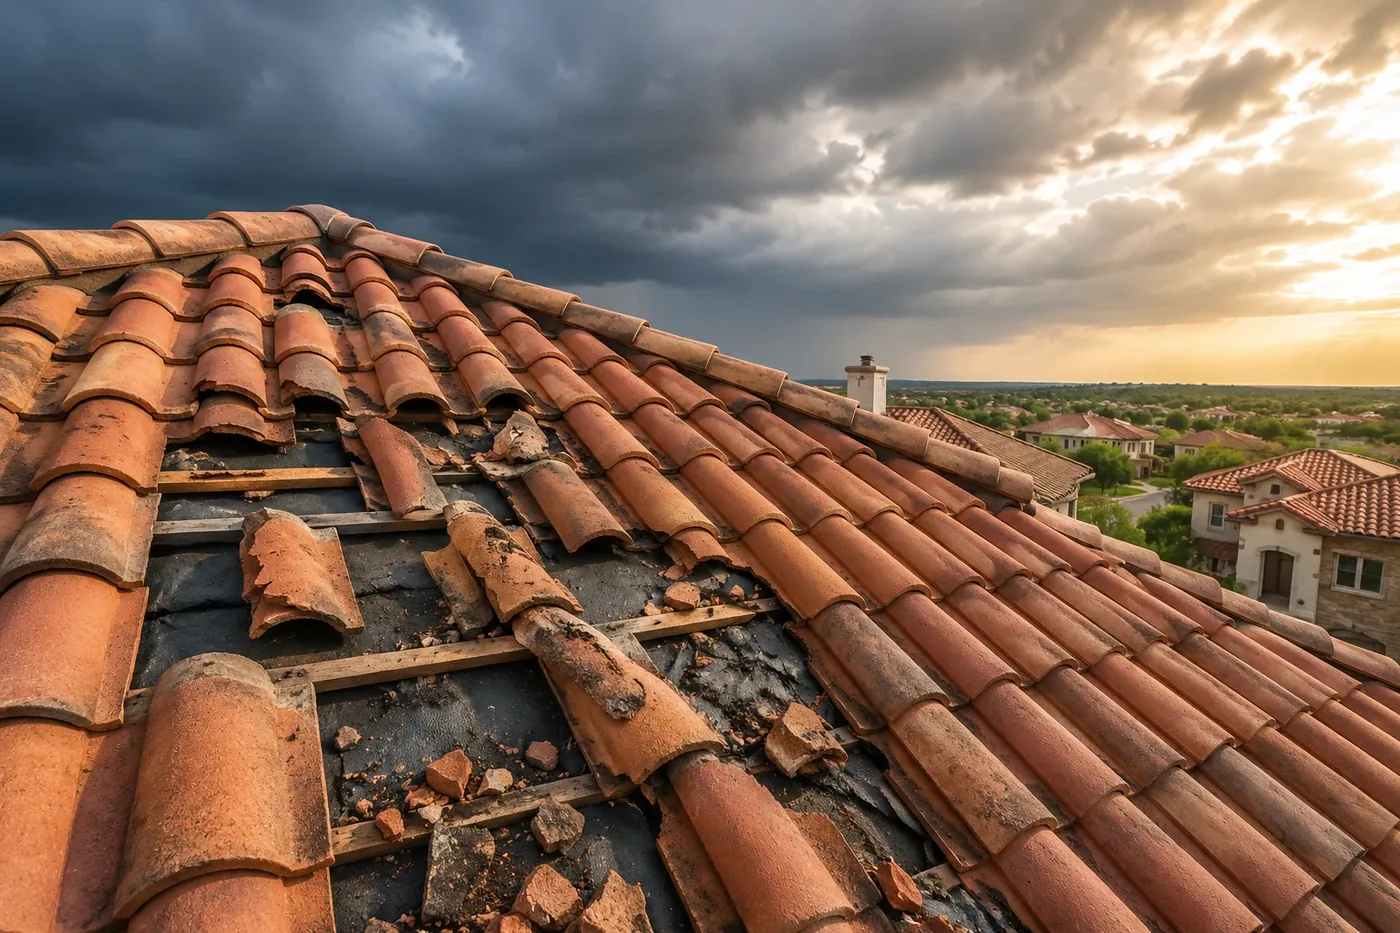
- Cracked, chipped or broken tiles and slates
- Split or broken wood shakes and shingles
- Damaged underlayment exposed by displaced pieces
Low-slope roofs
- Membrane fractures and punctures
- Seam separation
- Crushed insulation or cover board below the membrane
How insurance adjusters evaluate functional damage
Most carriers follow a similar inspection approach, although details vary by company and adjuster.
- Collateral damage check. The adjuster looks at gutters, downspouts, vents, screens, AC fins and soft metals for evidence of hail size and direction.
- Test squares. On sloped roofs, adjusters often mark a 10-by-10-foot test square on each slope and count qualifying hail hits. Many carriers use internal guidelines for how many hits justify replacing a slope. Those thresholds are carrier practices, not policy language.
- Close inspection of impacts. The adjuster presses on impact points to feel for soft spots or mat fractures and looks for exposed mat or punctures.
- Wind damage review. Lifted, creased or missing shingles are documented, sometimes with a lift test on sealed shingles.
- Repairability assessment. The adjuster considers whether damaged pieces can be replaced individually without harming surrounding materials.
Problems arise when the adjuster counts only obvious hits, misses mat fractures that require careful inspection, inspects only some slopes, or rushes during a busy storm season.
Why functional damage disputes happen
Functional damage disputes are common because the line between cosmetic and functional is not always visible to the naked eye. The most frequent sources of disagreement include:
- Hidden mat fractures. A bruise that looks minor on the surface may be fractured underneath.
- Age and wear. The carrier attributes granule loss or cracking to age rather than hail.
- Repairability. Brittle, discontinued or unmatched shingles may not be repairable without causing more damage, which can justify broader replacement.
- Test square thresholds. A slope that falls one or two hits short of the carrier's internal number may be denied even though it is clearly damaged.
- Cosmetic damage exclusions. Some Texas policies now include endorsements excluding cosmetic hail damage, especially for metal roofs, which raises the stakes on every classification.
Repairability: when functional damage justifies replacement
Even a carrier that agrees some shingles are functionally damaged may propose replacing only those pieces. Whether that works depends on the roof. Older shingles can become brittle, so lifting surrounding shingles to install replacements cracks them and creates new damage. Discontinued products may have no compatible replacement. And some manufacturers' installation requirements make piecemeal repairs impractical.
A simple field test helps: a roofer gently lifts a shingle tab and checks whether it bends or cracks. If shingles crack during a careful repair attempt, that evidence supports a broader replacement. Photograph or video the test and keep any damaged samples.
Mistakes that weaken a functional damage claim
- Waiting months to report the claim, which lets the carrier argue that damage came from a later event or from wear
- Making permanent repairs before the adjuster inspects
- Relying only on wide shots that do not show impact detail
- Letting the inspection happen without anyone present to point out damage
These issues often lead to denials of full roof replacement even when a roof is functionally compromised.
How to document functional roof damage
Strong documentation is the best way to show that damage affects function, not just appearance.
- Close-up photos with scale. Use a coin, ruler or chalk circle next to each impact so size is clear.
- Photos of every slope. Include overall shots and close-ups so the reviewer can see damage is widespread, not isolated.
- Collateral damage photos. Dented gutters, vents and AC fins help establish hail size and direction.
- Storm data. Hail reports for your address and date of loss from the National Weather Service or NOAA support causation.
- Roofer's written report. A contractor who explains mat fractures, brittleness or repairability carries weight.
- Interior evidence. Ceiling stains or attic leaks after the storm show that water-shedding ability was compromised.
- Shingle samples or test results. Brittleness tests or removed samples can show whether repairs are feasible.
Our free claim documentation checklist can help you organize everything in one place.
Functional damage in Texas roof claims
Texas homeowners deal with functional damage questions more than most. Hail is frequent across the Panhandle, West Texas, North Texas and Central Texas, and many neighborhoods see repeated storms over the life of a single roof. That creates two common Texas problems.
First, carriers may argue that damage came from an earlier storm or from age rather than the date of loss being claimed. Second, roofs that have taken several smaller hits may be brittle enough that repairs are no longer practical. Homeowners in hail-prone areas such as Amarillo, Lubbock and Dallas–Fort Worth should document their roofs after every significant storm. Our Amarillo insurance appraiser page covers Panhandle hail claims.
Texas also has rules that keep the process moving. Insurance Code chapter 542 requires carriers to acknowledge claims and make decisions within set timeframes, and chapter 542A generally requires 61 days' notice before suing on a weather claim.
Can appraisal resolve functional damage disputes?
Often, yes. If the carrier accepts that a storm occurred and some damage is covered, but disagrees on how much of the roof is functionally damaged, the policy's appraisal clause gives you a path to resolution. Each side names an appraiser, the appraisers inspect and price the damage, and an umpire decides disagreements.
Under State Farm Lloyds v. Johnson (Tex. 2009), Texas appraisers can assess the extent of damage and causation as part of determining the amount of loss, but they do not decide coverage questions. That means appraisal is well suited to deciding how many slopes are functionally damaged or whether the roof is repairable. Whether a cosmetic exclusion applies is a separate coverage question. This is general information, not legal advice.
See our guide to insurance appraisal for hail damage claims for how the process applies to roofs specifically.
Next steps if your roof damage was called cosmetic
If an adjuster labeled your roof damage cosmetic or approved only a few slopes, do not accept that conclusion without a second look. Get a qualified roofer's written assessment, gather photos and storm data, and ask the carrier to explain its classification in writing. If damage was overlooked entirely, our article on what to do if insurance missed roof damage walks through the next steps.
Frequently asked questions
What does functional damage mean on a roof?
Functional damage means harm that reduces a roof’s ability to shed water or shortens its expected service life. Examples include fractured shingle mats, punctures, creased or torn shingles, split wood shakes, cracked tiles and breached metal coatings. Damage that only changes appearance is usually called cosmetic instead.
How many hail hits per square does insurance require for a roof replacement?
There is no universal number in most policies. Many carriers use internal guidelines for counting hits in a 10-by-10-foot test square, and those thresholds vary by company. Repairability, brittleness, matching and damage on other slopes can also justify replacement even when a test square count is low.
Are dents on a metal roof functional damage?
Not always. Shallow dents with intact coating are often treated as cosmetic. Dents that crack the coating, deform seams, loosen fasteners or allow water entry are generally considered functional. Check your policy for a cosmetic damage exclusion, since that language can affect how metal roof dents are handled.
Can a roofer prove functional hail damage?
A qualified roofer can document functional damage with close-up photos, mat fracture findings, brittleness tests and a written report explaining why repairs are or are not feasible. Combined with storm data and collateral damage photos, that evidence carries weight with adjusters and appraisal panels.
What if my insurer says the roof damage is from age, not hail?
Ask the carrier to explain its conclusion in writing and provide inspection photos. Respond with storm data for your date of loss, collateral damage photos, maintenance records and a roofer’s report. If the dispute is about the extent of storm damage, appraisal may help resolve it under Texas law.

About the author: Joseph Dittman
Joseph is the lead appraiser at TX Insurance Appraiser and a Texas-licensed public adjuster (Rise Public Adjusting LLC, TDI license #3356839). He has spent his career inspecting hail, wind, water and fire losses and negotiating property claims across Texas. More about Joseph.
This article is general information about property insurance claims in Texas and is not legal advice. Policy language and facts vary; review your policy or consult a Texas attorney for legal questions.