Key takeaways
- Denials usually cite limited damage, age, maintenance, prior storms, or cosmetic exclusions.
- Carrier test-square thresholds are internal guidelines, not policy language.
- Matching, brittleness, and code requirements are strong arguments for full replacement.
- Get the denial reasons in writing and an independent inspection of every slope.
- If storm damage is accepted but extent is disputed, appraisal may resolve it.
Insurance companies deny full roof replacement most often because they conclude the storm damage is too limited, cosmetic, or repairable, or because they attribute damage to age, wear and tear, poor maintenance, or a prior event. A partial repair approval is not always the final word: matching, code, and evidence can change the outcome.
Few claim letters frustrate Texas homeowners more than the one that approves "repairs" to a roof the homeowner's roofer says must be replaced. Sometimes the carrier is right. Often, the disagreement comes down to how the damage was inspected, documented, and interpreted.
This guide explains why insurance companies deny full roof replacement, how carriers evaluate roof damage, the role of matching and engineering reports, and what you can do when you believe your roof qualifies for replacement.
How insurance companies evaluate roof damage
Every roof claim turns on two separate questions: Is there damage, and is that damage covered? An adjuster may agree your roof is worn and leaking yet deny replacement because the cause is not a covered peril.
| Condition | Typically covered? |
|---|---|
| Hail damage | Often covered (subject to deductibles and any cosmetic exclusions) |
| Wind damage | Often covered |
| Fire or falling-tree damage | Usually covered |
| Wear, tear, and deterioration | Usually excluded |
| Faulty installation or workmanship | Often excluded |
| Neglect or lack of maintenance | Often excluded |
Once the adjuster attributes damage to a covered event, the next question is extent: how many shingles, slopes, or components are damaged, and does repair restore the roof to its pre-loss condition?
Common reasons insurance companies deny full roof replacement
Insufficient storm damage
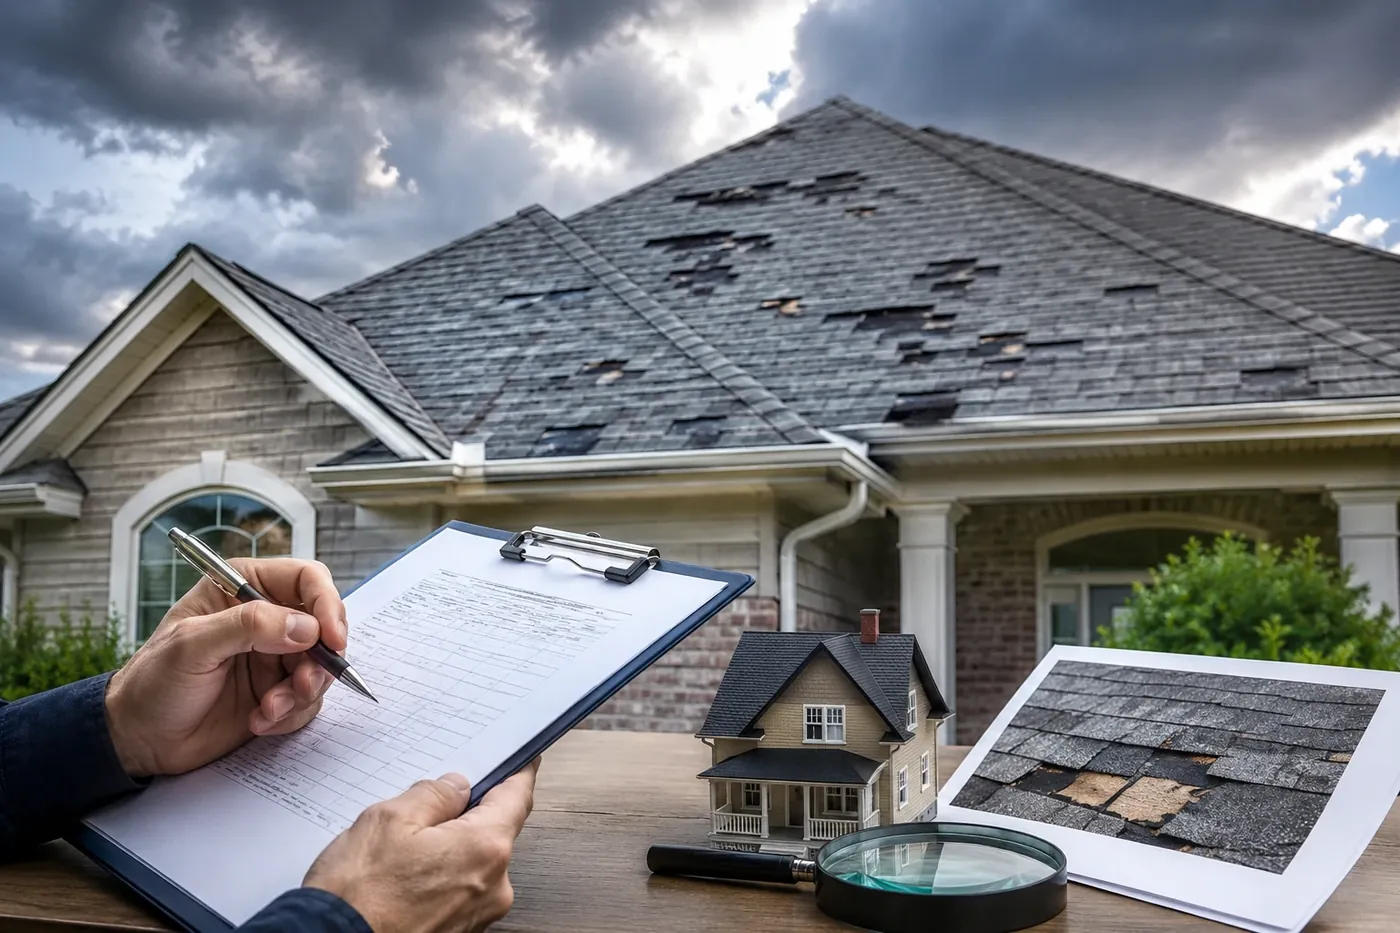
Many carriers use a "test square" approach, counting hail hits in a 10-by-10-foot area on each slope. If the count falls below the carrier's internal threshold, the adjuster may approve only individual shingle repairs. Those thresholds are carrier guidelines, not policy language, and they vary.
Roof age and wear-and-tear exclusions
Older roofs show granule loss, cracking, and blistering that adjusters may attribute to age rather than the storm. Distinguishing fresh hail fractures from long-term deterioration is often the heart of the dispute.
Improper maintenance or installation
Carriers may cite missing nails, improper overhang, debris buildup, or poor ventilation as the true cause of damage. Some of these conditions are excluded; others are irrelevant to whether hail or wind also damaged the roof.
Pre-existing or prior-storm damage
If the carrier believes damage came from an earlier storm, especially one outside the current policy period or a previously paid claim, it may deny or limit replacement. Accurate dates of loss matter here.
Cosmetic damage determinations
Some Texas policies, particularly for metal roofs, include cosmetic damage exclusions. If dents do not affect the roof's ability to shed water, the carrier may deny replacement. Learn the difference between cosmetic damage and functional damage in roof claims.
Why partial repairs are often approved instead
Insurance policies generally promise to repair or replace damaged property with materials of like kind and quality. They do not promise a new roof whenever any part is damaged. If a carrier believes targeted repairs restore the roof, it will usually scope repairs.
For example, if a carrier finds hail damage on one slope only, it might approve that slope plus a few ridge caps rather than the whole roof. The question is whether that repair truly works.
Repairs may be appropriate when:
- Damage is isolated to a small, clearly defined area
- Matching replacement shingles are available
- The remaining roof is in good, serviceable condition
- Repairs can be made without damaging surrounding shingles
Texas homeowners should also check whether a repair-only estimate even exceeds the deductible. Many Texas policies carry a wind and hail deductible set as a percentage of dwelling coverage, so a modest repair scope may produce no payment at all. That is one reason the repair-versus-replace question carries so much weight here.
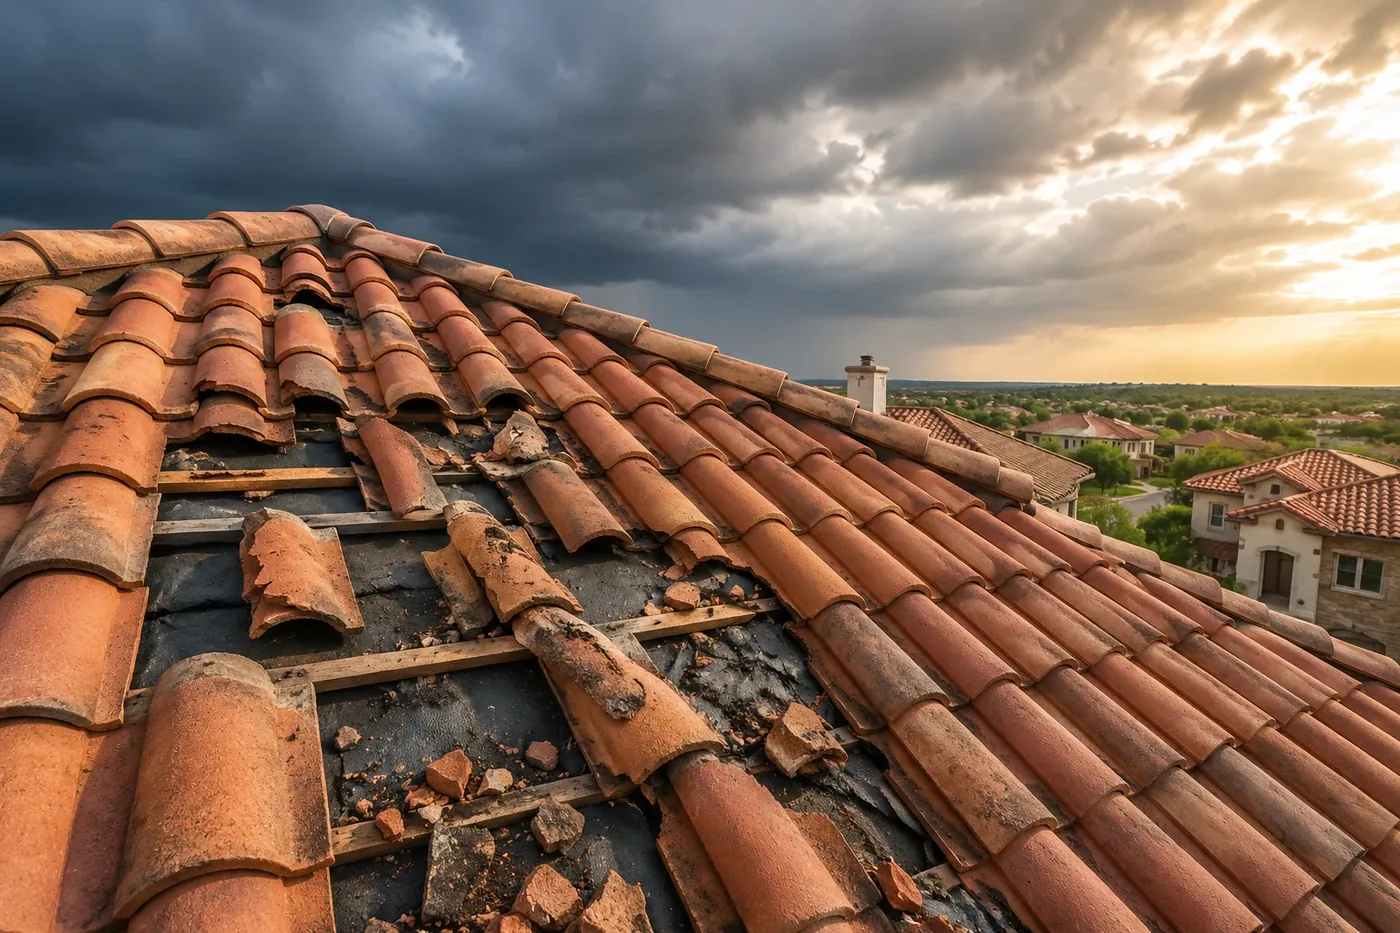
Repairs are often not workable when shingles are brittle, discontinued, or would break when lifted, or when local code requires replacement of an entire section.
Matching issues and partial roof replacement disputes
Matching is one of the strongest arguments for full replacement. If replacement shingles do not reasonably match the existing roof in color, style, or dimension, a patched roof can look obviously mismatched and, in some cases, may not seal properly with older shingles.
How matching is handled depends on your policy language and the facts. Some Texas policies address matching directly; others are silent. Discontinued shingle styles, faded colors, and size differences between older and newer products all support a matching argument. See matching issues in insurance claims for more.
Why contractors and insurance adjusters disagree
Roofers and adjusters look at the same roof through different lenses. Contractors focus on what it takes to restore a reliable, code-compliant, warrantable roof. Adjusters focus on what the policy requires the carrier to pay for the specific covered damage.
Neither lens is automatically right. The best outcomes come from evidence both sides can evaluate: clear photos of hail fractures, test square counts, brittleness tests, manufacturer guidance, and code citations.
The role of engineering reports
Carriers sometimes hire engineers to evaluate whether damage was caused by hail, wind, or other factors. These reports can be thorough, but they are not the final word. Look at how many slopes were inspected, what methods were used, and whether conclusions match the photos. An independent inspection may reach a different conclusion.
Texas hail claims and full roof replacement disputes
Texas leads the nation in hail claims, with frequent large-hail events across Dallas–Fort Worth, Plano, the Panhandle, and Central Texas. Repeated storms make it harder to separate new damage from old, which is exactly where full replacement denials arise.
Signs that may support full replacement include:
- Hail fractures (bruises with broken mat) distributed across multiple slopes
- Damage to soft metals, vents, and gutters consistent with the same storm
- Brittle shingles that crack or tear during repair attempts
- Discontinued products that cannot be matched
- Code requirements triggered by repairs above a certain scope
Document quickly. Hail damage weathers over time, and the longer you wait, the easier it is for a carrier to argue the damage is old. Storm data from the National Weather Service can help confirm the date of loss. For more on the process, see insurance appraisal for hail damage claims.
How to strengthen a roof replacement claim
- Get an independent roof inspection. A thorough inspection that covers every slope, with test squares and close-up photos.
- Document everything. Date-stamped photos of shingles, soft metals, gutters, and interior leaks.
- Understand your policy. Review the provisions below.
- Request a written explanation. Ask the carrier to explain in writing why it denied full replacement and what evidence it relied on.
- Request a re-inspection with your roofer present. Many disputes resolve when both sides walk the roof together.
| Policy provision | Why it matters |
|---|---|
| Replacement cost vs. actual cash value | Determines whether depreciation is recoverable after repairs |
| Roof surface or cosmetic exclusions | May limit payment for dents or appearance-only damage |
| Wind/hail deductible | Often a percentage of dwelling coverage in Texas |
| Matching language | Affects partial versus full replacement |
| Ordinance or law coverage | Pays some code-required upgrades |
If your roof is covered on an RCV basis, our recoverable depreciation calculator shows how much may be released once repairs are complete.
Warning signs your roof claim may be undervalued
A repair-only approval deserves a closer look when you see any of these red flags:
- The adjuster inspected only one or two slopes, or did not get on the roof at all
- The estimate ignores damaged vents, flashing, gutters, or other soft metals
- The repair scope is below or barely above your wind and hail deductible
- Neighbors with similar roofs from the same storm received full replacements
- No one addressed whether replacement shingles are available to match
Questions worth asking your carrier in writing: Which slopes were inspected? What hail count was found on each? What product was identified, and is it still manufactured? What evidence supports a wear-and-tear finding? Clear answers either explain the decision or reveal gaps you can challenge.
When appraisal can resolve a roof replacement dispute
If the carrier accepts that the storm damaged your roof but approves only repairs, the disagreement is often about the amount of loss: how much of the roof is damaged and what it takes to fix it. That kind of dispute can typically go to appraisal under your policy.
Texas appraisers may consider the extent of damage and causation as part of the amount of loss, though they do not decide coverage. An appraiser who knows roofing and estimating can present the evidence for replacement directly to the panel. Read can appraisal be used for roof claims to see how it works.
Appraisal is less helpful when the carrier denies the claim entirely on coverage grounds, such as claiming all damage is wear and tear. In those cases, legal advice may be needed. This is general information, not legal advice.
Next steps after a roof replacement denial
Insurance companies deny full roof replacement for reasons that range from legitimate to debatable: limited damage, age, maintenance, prior storms, and cosmetic exclusions. The denial is the carrier's position, built on one inspection and one interpretation.
Get the denial reasons in writing, gather independent evidence, and focus on matching, brittleness, and code. If the carrier accepts storm damage but will not agree on how much, appraisal offers a practical path to a binding amount of loss.
Frequently asked questions
Why would insurance pay for roof repair instead of replacement?
Insurers generally owe the cost to restore damaged property, not a new roof whenever any part is damaged. If the adjuster finds damage limited to certain slopes or shingles and believes matching materials are available, the carrier will often approve repairs. Brittle shingles, discontinued products, and code requirements can make repairs unworkable and support replacement.
How many hail hits are needed for a full roof replacement?
There is no universal number. Many carriers use internal guidelines based on hail hits per 10-by-10-foot test square on each slope, but those thresholds vary and are not written into most policies. What matters is whether the damage is functional, how widespread it is, and whether repairs can restore the roof.
Can I get a full roof replacement if shingles don't match?
Possibly. If replacement shingles cannot reasonably match the existing roof in color, style, or size, matching can support replacing more than the damaged area. Whether your policy requires it depends on its language and the facts. Documentation that your shingle is discontinued or that available products differ significantly strengthens the argument.
What should I do if my insurer says my roof damage is wear and tear?
Ask for the decision and supporting evidence in writing, then get an independent inspection focused on distinguishing storm damage from age-related wear. Weather data, dated photos, and damage to soft metals can show the storm's impact. If the carrier accepts some storm damage but disputes extent, appraisal may help; pure coverage denials may need legal advice.
Does a percentage wind and hail deductible affect roof replacement?
Yes. Many Texas policies use a wind and hail deductible calculated as a percentage of dwelling coverage, which can be several thousand dollars. A repair estimate that falls below the deductible results in no payment, so the difference between repair and full replacement can determine whether you receive anything at all.

About the author: Joseph Dittman
Joseph is the lead appraiser at TX Insurance Appraiser and a Texas-licensed public adjuster (Rise Public Adjusting LLC, TDI license #3356839). He has spent his career inspecting hail, wind, water and fire losses and negotiating property claims across Texas. More about Joseph.
This article is general information about property insurance claims in Texas and is not legal advice. Policy language and facts vary; review your policy or consult a Texas attorney for legal questions.