Key takeaways
- Insurance estimates measure covered loss; contractor estimates price the full job.
- Missing scope items usually create bigger gaps than unit pricing.
- Depreciation, code items and overhead and profit explain many differences.
- A line-by-line comparison with supporting documents is the best response.
- Appraisal can resolve scope, pricing and O&P disputes when coverage is not contested.
Insurance estimates are often lower than contractor estimates because they are built for different purposes. Carriers price covered damage with software databases, may pay actual cash value first, and frequently scope less work, while contractors bid the full job they will perform, including code items, overhead and profit, and real-world labor and material costs.
Few things frustrate Texas property owners more than seeing an insurance estimate that is thousands of dollars below a contractor's proposal for the same damage. One number seems too low, the other may seem too high, and the homeowner is caught in the middle. The truth is that both estimates can be prepared in good faith and still be far apart. Understanding why helps you close the gap with evidence rather than guesswork.
What is the difference between an insurance estimate and a contractor estimate?
What is an insurance estimate?
An insurance estimate is the carrier's calculation of what it owes under the policy for covered damage. It is usually prepared in Xactimate or Symbility, lists line items with quantities and unit prices, and then applies depreciation, the deductible and any prior payments. Its goal is to measure the covered loss, not to plan a construction project.
What is a contractor estimate?
A contractor estimate is a bid to perform the actual work. It reflects the contractor's real costs for labor, materials, equipment, permits, disposal, supervision and profit, plus any work needed to meet code or manufacturer requirements. Some contractors write detailed line-item estimates; others submit a single lump-sum price.
| Factor | Insurance estimate | Contractor estimate |
|---|---|---|
| Purpose | Measure covered loss under the policy | Price the full job the contractor will build |
| Pricing source | Estimating software price lists by region | Actual supplier quotes, crew costs and market conditions |
| Scope | Damage the adjuster observed and accepted | Everything needed to complete the repair properly |
| Depreciation | Often withheld until work is done (on RCV policies) | Not applicable |
| Overhead and profit | Sometimes omitted or disputed | Built into the price |
| Code upgrades | Depends on ordinance or law coverage | Included when required for a permit |
How does insurance pricing software affect estimates?
Most carriers use Xactimate, and some use Symbility. These platforms publish regional price lists that are updated periodically. They are a reasonable starting point, but price lists can lag behind sudden changes such as post-storm labor shortages or material price spikes. Pricing also varies by ZIP code, which we explain in why Xactimate estimates differ by ZIP code. A home in Dallas and a home in a small West Texas town may be priced differently for identical work.
Software also only prices what the estimator enters. If a line item is left out or the quantity is low, the software cannot correct it. That is why scope is usually a bigger issue than unit pricing.
Price lists can be challenged. If local suppliers or crews are charging more than the software reflects, invoices, supplier quotes and documented market conditions can support an adjustment. Estimators can also override line-item prices when evidence justifies it, which is why a well-documented estimate in the same platform the carrier uses is so effective. Our Xactimate estimate services are built for exactly that comparison.
Why are scope differences often the biggest problem?
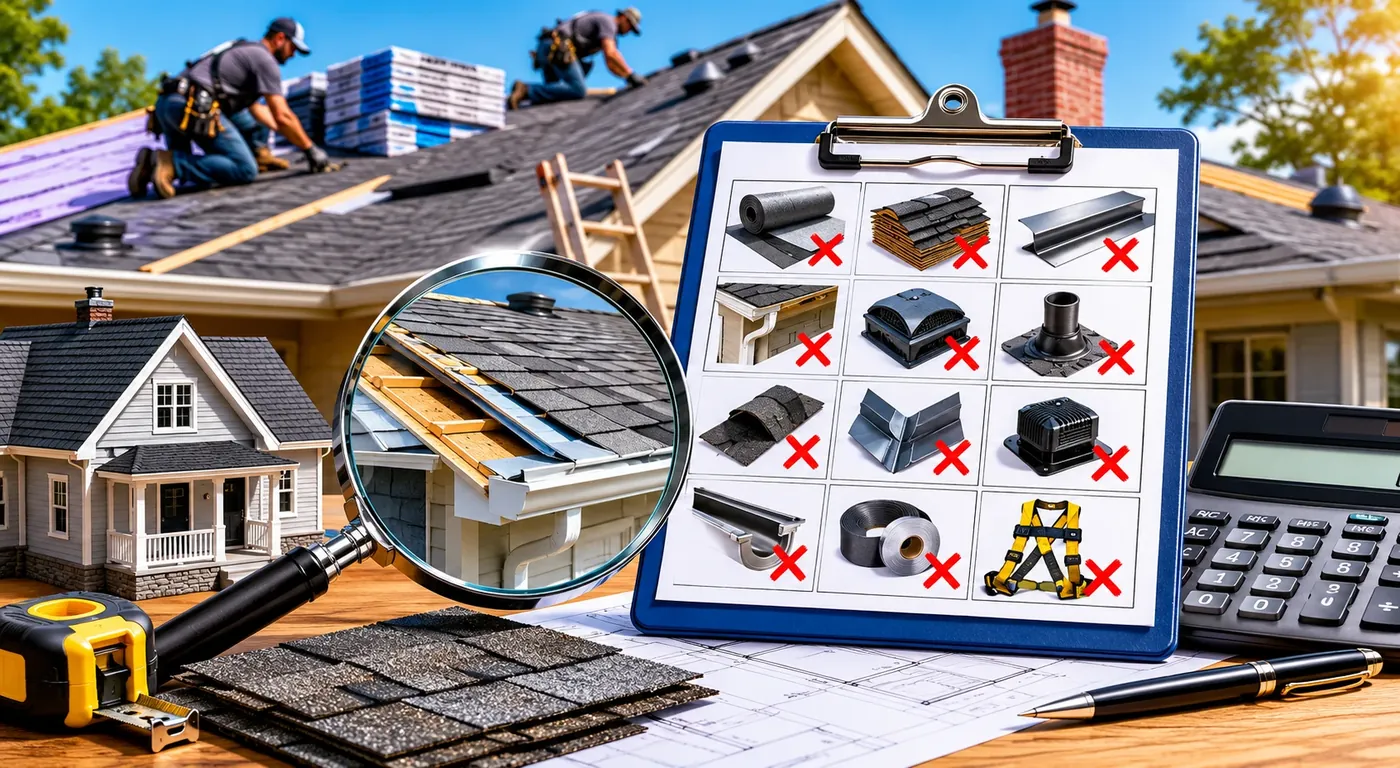
When we compare carrier and contractor estimates line by line, the largest gaps usually come from missing work, not unit prices. Common examples include:
- Roof flashing, vents, pipe jacks, starter, ridge cap and drip edge.
- Steep and high charges on steep-pitch or two-story roofs.
- Detach and reset of gutters, satellite dishes, solar panels or HVAC units.
- Drywall, insulation, paint and trim beyond the immediate stain area.
- Content manipulation, cleaning, drying equipment and debris removal.
Measurement differences matter too. A slightly smaller roof measurement or a lower waste factor reduces every related line item. Our roof square calculator helps you check squares, pitch and waste, and how roof waste factors affect insurance estimates explains why the waste percentage matters.
Repair versus replacement disputes
A carrier may estimate spot repairs when a contractor recommends full replacement. On a roof, that could mean replacing a few shingles instead of whole slopes; inside, it could mean patching drywall instead of replacing a wall. The disagreement often turns on whether repairs are feasible, whether materials can be matched and whether the repair will last. A repair-only estimate can be a fraction of a replacement estimate, so this single decision often explains most of the difference between two bids.
How do building codes and ordinance coverage affect the gap?
When work requires a permit, Texas cities may require it to meet current code, which can add items like drip edge, ice-and-water barrier, ventilation, upgraded electrical or decking repairs. Contractors include those items because the job cannot pass inspection without them. Insurance estimates may leave them out if the adjuster did not consider code or if the policy limits ordinance or law coverage. See ordinance and law coverage explained for how this coverage generally works.
Why do labor, materials, and overhead and profit cause disagreements?
After a major Texas storm, roofing crews and materials can be in short supply, and prices may rise faster than software price lists update. Contractors also price small jobs differently from large ones because mobilization costs are similar either way.
Overhead and profit (often called O&P) is another frequent gap. Contractors charge it on every job. Carriers sometimes leave it out, particularly when they believe a general contractor is not needed. When a project requires coordinating multiple trades, such as roofing, drywall, painting and electrical, many policyholders argue O&P should be included.
How does hidden damage change estimates?
Many estimates are written before demolition. Once a roofer removes shingles or a contractor opens a wall, they may find rotted decking, wet insulation, damaged framing or mold. That hidden damage was not in the original estimate because nobody could see it.
Common examples of hidden damage include:
- Rotted or delaminated roof decking discovered during tear-off.
- Wet insulation and drywall behind walls after wind-driven rain.
- Water that has wicked into subfloors, baseboards and cabinets.
- Damaged electrical wiring or ductwork behind ceilings.
- Mold growth that requires containment and remediation.
The fix is documentation. Photograph hidden damage when it is uncovered, before it is repaired, and submit it to the carrier as a supplement. Read supplemental insurance claims explained for how that process works.
Where do estimate differences show up most in Texas?
- Roof claims: hail and wind across Dallas-Fort Worth, Austin, San Antonio, Waco and the Panhandle create constant scope and pricing disputes.
- Water damage claims: drying, demolition and mold-related work are often underestimated.
- Fire and smoke claims: cleaning versus replacement and odor removal can produce large gaps.
- Commercial claims: big roofs, specialty systems and code requirements magnify small differences.
Texas adds its own pressures. Large hail events can damage thousands of roofs in a single afternoon, and contractors in cities like Fort Worth, Austin and Houston may raise prices as demand surges while software price lists catch up.
How should you respond to an estimate discrepancy?
- Compare line by line. Ask your contractor to mark up the carrier's estimate or produce a matching line-item estimate.
- Separate scope from price. List missing items first, then pricing differences.
- Ask specific questions. Request the adjuster's photos, measurements and reasons for excluding items.
- Provide supporting documents. Code requirements, manufacturer instructions, supplier quotes and photos.
- Keep organized records of every estimate, letter and conversation.
- Understand depreciation. On replacement cost policies, part of the gap may be recoverable depreciation paid after repairs. Use our recoverable depreciation calculator to see how much.
An illustrative example
Here is a hypothetical breakdown of how a gap can form. Suppose a carrier's roof estimate shows $14,000 in replacement cost, and a contractor's bid is $21,000. A line-by-line comparison might show something like this:
| Source of difference | Example amount | Type of issue |
|---|---|---|
| Missing flashing, vents and drip edge | $2,400 | Scope |
| Steep charges not included | $1,300 | Scope |
| Lower waste factor | $700 | Measurement |
| Overhead and profit omitted | $1,600 | O&P |
| Unit pricing differences | $1,000 | Price |
In this example, most of the gap comes from scope and O&P rather than price. These figures are illustrative only, but the pattern is typical: once you sort the differences into categories, it becomes clear which items to argue and what evidence each one needs.
Common misconceptions about estimate differences
- "The contractor must be overcharging." Sometimes, but often the contractor simply included work the carrier left out.
- "The insurance company must be underpaying." Sometimes, but part of the gap may be depreciation that will be paid later.
- "The lowest estimate must be correct." The right number is the one that reflects the full scope at fair local prices.
Next steps: when insurance appraisal may help
If you have documented the gap and the carrier still will not move, the appraisal clause in most Texas policies offers a way to resolve amount-of-loss disputes without a lawsuit. Each side appoints an appraiser, and an umpire decides any items they cannot agree on. Appraisal fits scope, pricing, O&P and repair-versus-replace disputes well; it does not resolve coverage questions. This is general information, not legal advice; check your policy's appraisal clause.
TX Insurance Appraiser represents Texas policyholders as their appraiser, using line-item Xactimate and Symbility estimates to show exactly where the carrier's number falls short. Visit our insurance appraisal services page to learn more.
Frequently asked questions
Why is my insurance check less than my contractor's quote?
Your first check may reflect actual cash value, meaning the carrier withheld depreciation and subtracted your deductible. On replacement cost policies, some of that depreciation may be paid once repairs are complete. The rest of the gap usually comes from missing scope items, pricing differences, code items or overhead and profit.
Do insurance companies have to use my contractor's estimate?
No. A contractor estimate is evidence of the cost of repair, but carriers are not required to adopt it. A detailed line-item estimate in the same format as the carrier's, supported by photos and documentation, is much more persuasive than a lump-sum bid and makes differences easier to resolve.
What is overhead and profit on an insurance claim?
Overhead and profit, often called O and P, covers a general contractor's business costs and profit for coordinating a repair. Many carriers include it when a project requires several trades, while others omit it for simpler jobs. Whether it is owed depends on the facts and your policy, and it is a common appraisal issue.
Can I negotiate an insurance estimate?
Yes. Request the carrier's full estimate and photos, then submit a line-item comparison showing missing items and pricing differences with supporting documents. Ask for a reinspection or revised estimate in writing. If negotiation stalls and the carrier accepts that damage is covered, the appraisal clause may provide a binding resolution.
Why do Xactimate prices differ from what contractors charge?
Xactimate uses regional price lists that are updated periodically and may lag behind real-time changes in labor and material costs, especially after major storms. Contractors price from current supplier quotes and crew costs. Pricing can be adjusted with documentation such as supplier invoices or local market evidence.

About the author: Joseph Dittman
Joseph is the lead appraiser at TX Insurance Appraiser and a Texas-licensed public adjuster (Rise Public Adjusting LLC, TDI license #3356839). He has spent his career inspecting hail, wind, water and fire losses and negotiating property claims across Texas. More about Joseph.
This article is general information about property insurance claims in Texas and is not legal advice. Policy language and facts vary; review your policy or consult a Texas attorney for legal questions.